Structured Settlements 4Real®Blog 2026

Structured settlements expert John Darer reviews the latest structured settlements and settlement planning information and news, and provides expert opinion and highly regarded commentary. that is spicy, Informative, irreverent and effective for over 20 years.

  • Private Assets: The Shift Was Already Visible — New Insurance News Article Just Put a Number on It

    What New Article Really Shows

    Insurers aren’t planning to increase private‑asset exposure — they already have. A new article published March 20, 2026 in InsuranceNewsNet simply quantifies what we’ve been tracking: 88% of insurers now expect private assets to exceed 10% of their portfolios within two years.

    That’s a headline, but it’s not a revelation. It’s confirmation.

    Schedule BA: Where the Shift Was Visible All Along

    Anyone following insurer filings — especially Schedule BA, the U.S. statutory category for “Other Long‑Term Invested Assets” — has seen this migration unfolding for years. Schedule BA is where private‑equity fund interests, private‑credit vehicles, joint ventures, affiliated structures, and other Level 3 assets show up long before anyone writes a survey‑driven story.

    📎 Sidebar: What Schedule BA Doesn’t Stand For

    Schedule BA doesn’t stand for British Airways, and it definitely won’t get you upgraded on your next flight to LHR or LGW. It’s simply the U.S. statutory bucket for “Other Long‑Term Invested Assets,” the place where insurers park private‑equity funds, private‑credit vehicles, joint ventures, and other Level 3 holdings long before anyone writes a headline. If you want to see the shift before the surveys catch up, this is where it shows up first.

    The Pattern Is the Story

    Surveys don’t reveal the trend — they just add another data point to the same direction of travel. The filings have been telling this story for years. Today simply adds one more brick to the pile.

    Rock and roll.

    Insurers optimistic about their investments in 2026 – Insurance News | InsuranceNewsNet March 20, 2026

    Private Credit Contagion: Structured‑Settlement and Receivables Exposure Structured Settlements 4Real March 9, 2026

    Narrative Diffusion & Retail Echoes – BlackRock withdrawal restrictions and private‑credit liquidity stress (April 29, 2026)

    Last updated April 30, 2026

  • Private Credit Contagion: Why It Matters for Structured Settlement Annuitants and Receivables Investors

    by John Darer CLU ChFC MSSC CeFT RSP CLC, 4structures®

    🕵️‍♂️ Private Equity’s Quiet Build‑Up in Insurance

    Private equity’s influence in the insurance sector didn’t begin with the latest headlines. It has been building quietly for years, reshaping balance sheets and business models long before most consumers ever encountered the term “private credit.” Now that pieces of the story are starting to surface — a headline here, a chart there, a table row taken out of context — the real risk isn’t panic. It’s misunderstanding.

    I’m stepping in now because I can see where confusion is about to ignite. Before the tinder gets lit, consumers deserve a clear, grounded explanation of what’s happening, what isn’t, and how to interpret the noise without absorbing the fear.

    This isn’t a structured‑settlement story on its face. But it has direct implications for the people and investors who rely on structured‑settlement payment streams.

    🛡️ Why Annuitants Should Care

    Structured‑settlement payments are only as secure as the insurer making them. When insurers shift heavily into private credit, Level 3 assets, or affiliated‑fund loans, the stability of those long‑dated obligations changes.

    Key risks:

    🔹 Illiquid assets rising — Level 3 holdings are opaque and hard to value.

    🔹 Liquidity mismatches — Stress events can freeze or delay payments.

    🔹 PE‑owned insurers behave differently — Some use annuity assets to support affiliated private‑credit funds.

    🔹 Guaranty‑fund limits vary — Large obligations may not be fully protected.

    Annuitants don’t need to panic — but they do need to understand the landscape.

    💼 Why Receivables Investors Should Care

    Investors who buy structured‑settlement receivables often focus on discount rates and court orders. But the real risk sits upstream, inside the insurer’s general account.

    You’re not buying a bond. You’re buying an insurer’s promise.

    And that promise is backed by whatever assets the insurer holds.

    Risks that matter:

    📉 Liquidity stress can delay or reduce payments.

    🔍 Affiliated‑fund lending can mask deteriorating capital.

    ⚠️ Level 3 concentrations can hide valuation problems.

    🏚️ Runoff carriers may lack diversification.

    🏦 PE‑owned insurers may be more exposed to contagion.

    🛑 Guaranty‑fund caps may not cover the full receivable, or at all.

    The secondary market rarely prices these risks correctly.

    🔄 Case Study: Liberty → Lincoln → Protective → Resolution Life

    A real‑world example shows how structured‑settlement blocks migrate — and why investors must track the current risk‑bearing entity.

    1. Liberty Life Assurance Company of Boston (Original Issuer)

    Wrote structured‑settlement annuities for decades.

    2. Acquired by Lincoln Financial Group (2018)

    Lincoln purchased Liberty’s life and annuity business.

    3. Lincoln Reinsured the Block to Protective Life

    Protective became the reinsurer and took over customer service.

    4. Protective Ceded $9.7 Billion of Reserves to Resolution Life (2025)

    This included:

    • structured‑settlement annuities
    • secondary guaranteed universal life policies

    Protective retains administration, but Resolution Life now holds the economic exposure.

    Why Protective Did It

    💡 Reduce market risk 💡 Free up capital 💡 Support future acquisitions 💡 Strengthen core retail businesses

    Who Is Resolution Life?

    A global in‑force specialist managing closed blocks of life and annuity liabilities.

    Who Is Dai‑ichi Life Holdings?

    A major Japanese life‑insurance group and parent of Protective Life.

    📊 Structured‑Settlement Carrier Snapshot (Private‑Credit & Level 3 Exposure)

    All information in this section is drawn from public, regulator‑facing disclosures that every life insurer files, including statutory annual statements, NAIC investment schedules, SEC 10‑K filings (for public companies), and parent‑company asset‑management reports. The categories shown — such as private credit, Level 3 assets, and affiliated‑fund investments — reflect standard reporting classifications used across the industry. No inference of risk, instability, or concern is intended; the table simply summarizes information that insurers themselves report in their required filings.

    ACTIVE WRITERS (A–Z)

    • American General Life Insurance Company (Corebridge Financial)
    • American National Insurance Company (ANICO)
    • Athene Annuity and Life Company
    • Berkshire Hathaway Life Insurance Company of Nebraska
    • Independent Life Insurance Company
    • Metropolitan Life Insurance Company (MLIC)
    • Metropolitan Tower Life Insurance Company (MTL)
    • New York Life Insurance Company
    • Pacific Life Insurance Company
    • Prudential Insurance Company of America
    • Puritan Life Insurance Company of America
    • United of Omaha Life Insurance Company
    • USAA Life Insurance Company
    • United States Life Insurance Company in the City of New York (USLNY)

    ⭐ Footnotes for Active Writers (Alphabetical, PE‑Contagion Context + Level 3 Exposure)

    American General Life Insurance Company (Corebridge Financial) Corebridge is the AIG life‑and‑retirement spin‑off. While still a balance‑sheet insurer, it has increased allocations to private‑credit strategies and uses reinsurance partners with private‑equity affiliations. Exposure is moderate but rising. Corebridge’s private‑credit allocations include Level 3 components.

    American National Insurance Company (ANICO) Entered the structured‑settlement market in Q2 2025 and is an active writer. A traditional balance‑sheet insurer with meaningful private‑credit exposure but no private‑equity ownership. American National carries higher Level 3 exposure than Athene, placing it structurally above Athene in contagion sensitivity.

    Athene Annuity and Life Company Active structured‑settlement writer with material relevance for private‑credit contagion mapping. Athene Annuity and Life Company is an active structured‑settlement writer and a major issuer of fixed and retirement annuities. As part of Apollo’s retirement‑services platform, AAALC operates within a balance‑sheet model deeply integrated with private‑credit origination, asset‑backed finance, and affiliated reinsurance structures. The company maintains significant Level 3 exposure, consistent with its alternative‑asset‑driven investment strategy. AAALC’s scale, investment profile, and reinsurance architecture make it a key node in any analysis of potential transmission pathways between private‑credit stress and the insurance sector.

    Berkshire Hathaway Life Insurance Company of Nebraska A balance‑sheet insurer with minimal private‑equity influence. Berkshire’s investment strategy is internally controlled and avoids PE‑style leverage. Low contagion exposure.

    Independent Life Insurance Company Privately owned by Independent Insurance Group and not private‑equity‑owned. Uses significant reinsurance but maintains a conservative investment posture and a structurally simple balance sheet. Active SS‑exclusive writer. Low contagion exposure.

    Metropolitan Life Insurance Company (MLIC) MetLife’s flagship life insurer and one of its two active structured‑settlement writers. MetLife is not PE‑owned. Certain blocks have been reinsured to Global Atlantic (Apollo‑owned), creating indirect PE adjacency. Contagion exposure is low‑to‑moderate. MetLife has indirect Level 3 adjacency through Global Atlantic.

    Metropolitan Tower Life Insurance Company (MTL) Second active structured‑settlement chassis within MetLife. Shares the same indirect PE adjacency through MetLife’s reinsurance with Global Atlantic. Contagion exposure is low‑to‑moderate. MetLife has indirect Level 3 adjacency through Global Atlantic.

    New York Life Insurance Company Mutual insurer with no private‑equity ownership or influence. Conservative investment posture and minimal reliance on external reinsurers. Low exposure.

    Pacific Life Insurance Company Balance‑sheet insurer with diversified investments. Some reinsurance relationships touch PE‑linked entities, but Pacific Life retains control of its structured‑settlement liabilities. Moderate exposure. Pacific Life maintains moderate Level 3 exposure tied to private‑credit allocations.

    Prudential Insurance Company of America Prudential has executed reinsurance transactions with Fortitude Re (Carlyle‑linked), creating indirect PE adjacency. Core operations remain balance‑sheet driven. Moderate exposure. Prudential has indirect Level 3 adjacency through Fortitude Re’s private‑credit portfolio.

    Puritan Life Insurance Company of America Privately held and not private‑equity‑owned. Conservative investment posture with limited external reinsurance activity. Puritan’s structured‑settlement business is modest in scale but internally controlled. Low contagion exposure.

    United of Omaha Life Insurance Company Mutual insurer with no private‑equity ownership. Conservative investment posture and minimal external reinsurance reliance. Low exposure.

    United States Life Insurance Company in the City of New York (USLNY) NY‑domiciled Corebridge affiliate. Shares Corebridge’s moderate private‑credit exposure due to group‑level investment strategy and reinsurance relationships. Corebridge’s private‑credit allocations include Level 3 components.

    USAA Life Insurance Company Member‑owned insurer with no private‑equity ownership. Conservative investment strategy and limited use of external reinsurers. Low exposure.

    🗂️Sources — Active Writers

    • American General Life Insurance Company (Corebridge Financial) Ownership and group structure sourced from Corebridge Financial public filings and AIG separation disclosures. Private‑credit allocations and affiliated‑reinsurance relationships referenced from Corebridge statutory filings and rating‑agency reports (AM Best, S&P). Level 3 exposure derived from Corebridge statutory annual statements (Fair Value Measurements note and investment schedules).
    • American National Insurance Company (ANICO) Brookfield Reinsurance completed its $5.1 billion all‑cash acquisition of American National on May 25, 2022, at $190 per share (Brookfield Reinsurance completion announcement; Insurance Business America transaction coverage). Private‑credit allocations and Level 3 exposure derived from American National statutory annual statements (Fair Value Measurements note, Schedule BA, and related investment schedules).
    • Athene Annuity and Life Company Ownership and private‑credit strategy sourced from Apollo Global Management and Athene public filings. Level 3 exposure derived from Athene statutory filings and GAAP fair‑value hierarchy disclosures.
    • Berkshire Hathaway Life Insurance Company of Nebraska Ownership and investment posture sourced from Berkshire Hathaway statutory filings and Berkshire Hathaway Inc. annual reports. “Actively paused” issuance posture based on market‑wide structured‑settlement activity and Berkshire’s selective‑issuance history. No material Level 3 exposure relevant to contagion mapping.
    • Independent Life Insurance Company Ownership and business model sourced from Independent Insurance Group disclosures. Reinsurance structure and investment posture derived from statutory filings. No material Level 3 exposure relevant to contagion mapping.
    • Metropolitan Life Insurance Company (MLIC) Ownership and group structure sourced from MetLife Inc. public filings. Reinsurance relationships with Global Atlantic (Apollo‑owned) sourced from MetLife disclosures and regulatory filings. Level 3 adjacency derived from Global Atlantic statutory filings and fair‑value hierarchy notes.
    • Metropolitan Tower Life Insurance Company (MTL) Same ownership and reinsurance context as MLIC. Level 3 adjacency derived from Global Atlantic statutory filings and fair‑value hierarchy notes.
    • New York Life Insurance Company Ownership and investment posture sourced from New York Life public filings and statutory statements. No material Level 3 exposure relevant to contagion mapping.
    • Pacific Life Insurance Company Ownership and investment posture sourced from Pacific Life public filings and statutory statements. Private‑credit allocations and Level 3 exposure derived from Pacific Life statutory filings (Fair Value Measurements note and investment schedules).
    • Prudential Insurance Company of America Reinsurance transactions with Fortitude Re (Carlyle‑linked) sourced from Prudential public filings and regulatory disclosures. Level 3 adjacency derived from Fortitude Re statutory filings and fair‑value hierarchy notes.
    • Puritan Life Insurance Company of America Ownership and investment posture sourced from Puritan Life statutory filings. No material Level 3 exposure relevant to contagion mapping.
    • United of Omaha Life Insurance Company Ownership and investment posture sourced from Mutual of Omaha public filings and statutory statements. No material Level 3 exposure relevant to contagion mapping.
    • United States Life Insurance Company in the City of New York (USLNY) Ownership and group structure sourced from Corebridge Financial disclosures. Private‑credit allocations and Level 3 exposure derived from Corebridge statutory filings.
    • USAA Life Insurance Company Ownership and investment posture sourced from USAA public filings and statutory statements. No material Level 3 exposure relevant to contagion mapping.

    🏷️ Legacy Structured‑Settlement Block Holders (Alphabetical Order)

    All information in this section is drawn from public regulatory filings, statutory annual statements, parent‑company disclosures, and rating‑agency reports. Legacy carriers listed here no longer write new structured‑settlement business but continue to administer or hold legacy obligations. No inference of risk or instability is intended; this section summarizes publicly reported ownership, runoff status, and block‑migration history.

    AIG Life Insurance Company (Legacy — Not Corebridge)

    AIG Life Insurance Company was the historical AIG entity that wrote structured‑settlement annuities. This entity is not part of Corebridge Financial and is distinct from American General Life (AGL), United States Life of New York (USLNY), and VALIC, which are the active Corebridge writers today. AIG Life exited the structured‑settlement market years ago. Its remaining long‑duration liabilities were transferred to Fortitude Re, a runoff specialist owned by Carlyle and T&D Holdings.

    Allstate Life Insurance Company / Allstate Life of New York → Everlake Life / Wilton Re

    Allstate exited the life and annuity business through two transactions:

    • Allstate Life Insurance Company (ALIC) was sold to Blackstone and renamed Everlake Life Insurance Company.
    • Allstate Life Insurance Company of New York (ALNY) was sold to Wilton Re, which now administers the New York structured‑settlement block. Both Everlake and Wilton Re operate in runoff.

    Amica Life Insurance Company

    Amica previously wrote structured settlements but exited the market. It continues to administer its small legacy block.

    CNA (Continental Casualty Company)

    CNA exited structured‑settlement issuance years ago. Its legacy obligations remain on the books and are administered internally.

    Everlake Life Insurance Company (formerly Allstate Life Insurance Company)

    Everlake is the renamed Allstate Life Insurance Company, acquired by Blackstone. It does not write new structured‑settlement business and administers the legacy Allstate block (excluding New York, which went to Wilton Re).

    Genworth Life Insurance Company

    Genworth exited the structured‑settlement market long ago. The company remains in runoff and continues to administer its legacy obligations.

    Hartford Life Insurance Company

    Hartford sold its annuity and life blocks to Talcott Resolution (now owned by Sixth Street). Hartford no longer writes structured settlements; Talcott administers the legacy obligations.

    John Hancock Life Insurance Company

    John Hancock exited the structured‑settlement market and continues to administer its legacy block internally.

    MassMutual

    MassMutual previously wrote structured settlements but exited the market. It continues to administer its legacy obligations.

    Prudential of Japan

    Prudential’s U.S. entities no longer write structured settlements. The Japanese subsidiary historically held certain structured‑settlement obligations; these remain in runoff.

    Symetra Life Insurance Company

    Symetra exited structured‑settlement issuance after its acquisition by Sumitomo Life. It continues to administer its legacy block.

    Travelers Life & Annuity

    Travelers exited the structured‑settlement market decades ago. Its obligations were assumed by MetLife as part of the Travelers acquisition.

    Wilton Re (Wilcac Life, Wilton Reassurance Life of New York, etc.)

    Wilton Re does not write new structured‑settlement business. It is a legacy block acquirer, specializing in assumption reinsurance and runoff. Wilton Re subsidiaries administer structured‑settlement blocks acquired from Allstate NY, Transamerica, and others. Wilton Re is owned by CPP Investments.

    📁 Legacy Sources

    Ownership, runoff status, and block‑migration history sourced from:

    • Statutory annual statements
    • NAIC filings
    • Parent‑company disclosures
    • Rating‑agency reports (AM Best, S&P, Fitch)
    • Public acquisition and assumption‑reinsurance announcements (Allstate → Everlake; Allstate NY → Wilton Re; AIG Life → Fortitude Re; Hartford → Talcott Resolution)

    🎯 What Readers Should Take Away

    Whether you’re an annuitant, attorney, planner, or receivables investor, the message is simple:

    • Know your carrier
    • Know their ownership
    • Know their exposure.

    Private credit isn’t inherently bad.

    But opacity, leverage, and long‑duration promises don’t mix well.

    This piece gives readers the context they need — without overwhelming them.

    Abstract highlights

    • Shows that life insurers have increased their lending in the private placement market over the past decade, totaling $849 billion, or 14%, on life insurers’ balance sheets in 2024. A substantial part of the growth stems from private credit extension to financial borrowers and to privately placed asset-backed securities.
    • Authors document that private equity-owned (PE-owned) life insurers drive these trends. Authors also provide evidence that these investments have about 80 basis points higher spreads compared to public bonds and foster PE-owned insurers’ growth in the annuities market.
    • A one standard deviation increase in financial private placement investments is associated with 0.05 percentage points higher market share in the annuities market.

    US life insurers head offshore as private credit upends industry from Moodys Special Report Three steps life insurers are taking to thrive in a changing industry June 2, 2025

    • Partnering with alternative asset managers: Seeking better investment returns than were available from public fixed income investments, insurers began to team up or merge with private equity firms (also called alternative asset managers).
    • Shedding unprofitable businesses: Life insurers free up capital and reduce tail risk by offloading capital intensive, non-core business.
    • Moving nearly $800 billion in reserves offshore to affiliates: Sending the largest share to Bermuda, life insurers stay competitive and keep profits in house. Additionally, they have grown their own investment capabilities.
    • Why it matters: The new business model has thrived, but risks may surface due to lack of transparency and exposure to counterparty risk.

    Last updated March 26, 2026


  • ⚖️ New York Structured Attorney Fees and the $20,000 Retirement Exclusion (Updated for 2026)

    By John Darer® CLU ChFC MSSC CeFT RSP CLTC

    No. New York’s pension and annuity exclusion under NY Tax Law §612(c)(3‑a) applies only to qualified pension and annuity income. Structured attorney fees are non‑qualified deferred compensation, not employee‑based retirement income, and therefore do not qualify. This interpretation has remained consistent since TSB‑M‑81(19)R(1) (NYS Dept. of Taxation, 1982).

    🎂 Age Requirement

    The taxpayer must be 59½ or older during the tax year.

    💵 Amount of Exclusion

    The exclusion remains $20,000 per taxpayer. A 2025–2026 bill proposing an increase to $30,000 was stricken and did not become law.

    🧾 Federal AGI Requirement

    The income must be included in federal AGI before it can be subtracted on the New York return.

    📘 What Qualifies as Pension & Annuity Income

    New York allows the exclusion for:

    • periodic payments for services performed as an employee before retirement (NY Tax Law §612(c)(3‑a));
    • traditional IRA distributions included in federal AGI;
    • 401(k), 403(b), and 457(b) plan distributions;
    • Keogh (HR‑10) plan distributions;
    • employer‑purchased annuity contracts.

    These categories align with federal definitions of qualified plan distributions, which in 2026 follow updated IRC §415 limits (e.g., defined benefit limit $290,000; defined contribution limit $72,000; elective deferral limit $24,500; catch‑up $8,000) .

    🚫 What Does NOT Qualify

    structured attorney fees;

    non‑qualified annuities purchased personally;

    payments derived from contributions made after retirement;

    Roth IRA qualified distributions (not included in AGI);

    A structured attorney fee is:

    • self‑employment income, not employee wages;
    • non‑qualified deferred compensation, not a pension;
    • not paid from a qualified plan under IRC §§401–408;
    • not employer‑funded;
    • taxable when received, but still ordinary income.

    New York’s exclusion applies only to employee‑based retirement income, and the Department of Taxation has never expanded the definition to include structured fees. The controlling interpretation remains TSB‑M‑81(19)R(1).

    A structured attorney fee is a non‑qualified deferred compensation arrangement in which a lawyer elects to receive contingent fees over time. Key features include:

    • the election must occur before settlement is finalized;
    • payments must be part of the settlement agreement;
    • funding is typically through a qualified assignment;
    • payments are taxable when received, not when earned;
    • the arrangement is not ERISA, not a pension, and not a qualified plan.

    Structured fees are useful for cash‑flow smoothing and tax‑timing, but they do not convert into “pension income” under New York law.

    Several companies offer alternative attorney‑fee deferral programs, including market‑based deferrals, trust‑based structures, and non‑annuity assignment arrangements. Programs such as Jurisprudent and OptCapital fall into this category. While these platforms differ in how deferred fees are invested or administered, New York treats all of them the same way for tax purposes. They are all non‑qualified deferred compensation, not employer‑sponsored retirement plans, and therefore do not qualify for New York’s $20,000 pension and annuity exclusion (NY Tax Law §612(c)(3‑a); TSB‑M‑81(19)R(1)). The branding, investment strategy, or platform used does not convert attorney fees into “pension income” under New York law.

    💬 Can a New York attorney structure fees if the funds are already in an IOLTA account?

    No. Constructive receipt has occurred; deferral is no longer possible.

    💬 Can a New York partnership deduct structured fees paid to partners?

    No. Payments to partners are treated as distributive share or guaranteed payments.

    💬 Can a sole proprietor deduct structured fees paid to themselves?

    No. You cannot deduct payments to yourself.

    💬 Are structured attorney fees subject to ERISA?

    No. They are non‑qualified arrangements.

    💬 Are structured attorney fees “pension plans”?

    No. They do not meet the definition of a qualified pension, annuity, or retirement plan under federal or New York law.

    Retired New York lawyers cannot use the $20,000 pension and annuity exclusion for structured attorney fee income. The exclusion remains limited to qualified retirement income, and structured fees remain ordinary income when received, regardless of age or payment form.

    Related Reading


  • Discover Pacific Life’s Payout Plus: Index-Based Growth

    by John Darer CLU ChFC MSSC CeFT RSP CLTC

    In March 2026 Pacific Life announced the launch of Payout Plus, a unique structured settlements annuity benefit option that redefines what’s possible in settlement planning. Payout Plus offers stability with significantly more room to grow.

    Payout Plus Offers an Indexed-Based Structured Settlement design

    with meaningful opportunities for structured settlement payees to receive more than the guaranteed baseline payment.

    “Structured settlements are built on the promise of long-term financial security,” said Geoffrey Kissel, vice president of structured settlements at Pacific Life. “With Payout Plus, we’re taking that promise a step further by adding a benefit option that offers structured settlement consultants and their clients a new way to handle life’s financial curveballs while maintaining the reliability of guaranteed income.”

    Payout Plus is available with Pacific Life’s structured settlements annuity contracts and is designed for individuals receiving settlements from personal injury or workers’ compensation cases. It also can be used to structure attorney fees for these types of settlements. In addition, Payout Plus offers the opportunity for claimants to achieve greater financial flexibility over time.

    • The potential for increases in payments.
    • A guaranteed minimum payment, with amounts that may fluctuate—but never fall below that minimum.
    • Flexible options to help meet a wide range of claimant needs.

    “For claimants seeking more than just fixed payments, Payout Plus opens the door to a new kind of structured settlements strategy,” said Kevin Kennedy, senior vice president and chief sales and marketing officer, consumer markets at Pacific Life. “Payout Plus reflects our commitment to helping people stay financially resilient throughout their lives. We’re excited to forge a path that empowers both claimants and their consultants to rethink what’s possible.”

    A whale breaching the surface of the ocean against a sunset background, with a rising graph line overlay indicating growth.

    Please Note that at the time of publication Payout Plus is not yet available for cases with a nexus to New York

  • by John Darer CLU ChFC MSSC CeFT RSP CLTC

    Long‑Term Services and Supports (LTSS) is one of those policy terms that feels abstract until it becomes the center of someone’s life. It becomes real the moment a person can no longer perform daily activities without help — bathing, dressing, eating, managing medications, or simply navigating a home that no longer fits their body. This is why LTSS and structured settlements must be understood together — not as separate planning concepts.

    For injury victims, medically fragile children, and adults with chronic conditions, LTSS isn’t a category. It’s the infrastructure of daily survival.

    And yet, in far too many settlements, LTSS needs are treated as a footnote — or worse, a negotiable inconvenience.

    This is where structured settlement planning and disciplined settlement design matter. LTSS is long‑term by definition. The funding strategy must be long‑term as well.

    Why LTSS Should Reshape How We Think About Settlements

    LTSS is not a single service. It’s an ecosystem:

    • Home‑ and community‑based services (HCBS)
    • Personal care attendants
    • Adult day programs
    • Residential supports
    • Assistive technology
    • Transportation
    • Care coordination
    • Respite for family caregivers

    These supports are not “extras.” They are the scaffolding that allows someone to live with dignity, autonomy, and safety.

    The challenge? LTSS is expensive, ongoing, and highly variable over a lifetime. Needs escalate. Care models shift. Family caregivers burn out. Medicaid eligibility changes. Private‑pay costs rise faster than inflation.

    A lump sum cannot reliably track that complexity. A structured settlement can.

    🏛️ The Policy Backdrop: What the LTSS Crisis Looks Like From 30,000 Feet

    In January 2026, InsuranceNewsNet ran a piece by Susan Rupe asking a blunt question: Can government ease the long‑term care crisis? The article captures a national tension that directly affects settlement planning.

    1. The demographic math is unforgiving

    America is aging faster than its care infrastructure can adapt. Demand for LTSS is rising while the workforce available to provide it is shrinking.

    2. Medicaid is carrying the load — and it’s buckling

    Medicaid has become the country’s de facto long‑term care insurer. But HCBS waivers are strained, reimbursement rates lag behind actual costs, and states are struggling to keep people out of institutional settings.

    See also: Medicaid eligibility traps.

    3. Private LTC insurance is not the cavalry

    The traditional LTC insurance market has contracted. Carriers have exited, premiums have spiked, and remaining products are narrower and less predictable.

    4. Government “solutions” are still conceptual

    Rupe highlights proposals — tax credits, public‑private hybrids, caregiver support — but none are close to implementation.

    Translation for settlement planning: If you’re counting on government or private insurance to stabilize LTSS, you’re already behind.

    🔗 Why This Matters for Structured Settlements

    Rupe’s article reinforces a truth the settlement industry often avoids: LTSS is not a problem government or insurance carriers are going to solve for your client.

    That leaves only one place where stability can be engineered: the settlement itself.

    Structured settlements become a counterweight to systemic uncertainty:

    • When Medicaid waiver slots freeze, structured income keeps care going.
    • When caregiver shortages drive up private‑pay rates, indexed payments absorb the shock.
    • When policy proposals stall, the structure doesn’t.
    • When families face burnout, predictable funding buys respite and coordination.

    Structured settlements aren’t just financial tools — they are LTSS risk‑management tools.

    How Structured Settlements Support LTSS Stability

    Structured settlements introduce what LTSS inherently requires: predictability, durability, and protection from volatility.

    1. Guaranteed, tax‑free income for life

    Payments can be designed to:

    • Increase over time as care needs escalate
    • Layer monthly income with periodic lump sums
    • Provide lifetime benefits for individuals with permanent disabilities

    See: lifetime structured settlement payments.

    2. Protection from premature depletion

    LTSS is a marathon. Structures prevent the sprint‑and‑collapse pattern that devastates families relying on lump sums.

    See: lump‑sum risk.

    3. Medicaid‑compatible planning

    When coordinated with a trust, structured settlements can:

    • Preserve Medicaid eligibility
    • Fund HCBS services
    • Provide supplemental supports without triggering resource limits

    This is where settlement planning becomes a discipline, not a transaction.

    🧩 Where Special Needs Trusts Fit In (Supplemental Needs Trusts in New York)

    LTSS doesn’t exist in a vacuum. It sits inside a benefits ecosystem — Medicaid, SSI, HCBS waivers — that can collapse instantly if assets are titled incorrectly.

    This is where Special Needs Trusts — or Supplemental Needs Trusts under New York’s EPTL § 7‑1.12 — become essential.

    An SNT:

    • Preserves Medicaid/SSI eligibility
    • Receives structured settlement payments
    • Pays for supplemental supports Medicaid won’t cover
    • Can make annual contributions to an ABLE account (up to the federal limit)
    • Must comply with New York’s supplemental‑needs statutory language

    Effective January 1, 2026, ABLE eligibility expands to age 46, allowing SNT trustees to fund ABLE accounts for a far larger population of beneficiaries. This adds a flexible, beneficiary‑controlled layer to LTSS planning without jeopardizing Medicaid or SSI.

    See also: ABLE accounts and structured settlements.

    LTSS Funding Flow: Structured Settlement → SNT → ABLE → Lifetime Supports

                ┌────────────────────────────────────────┐
                │   INJURY / DISABILITY / LTSS NEEDS     │
                └────────────────────────────────────────┘
                                   │
                                   ▼
                ┌────────────────────────────────────────┐
                │   SETTLEMENT PROCEEDS (Gross Recovery) │
                └────────────────────────────────────────┘
                                   │
                     (Risk: Lump sum triggers Medicaid loss)
                                   │
                                   ▼
        ┌────────────────────────────────────────────────────────┐
        │   STRUCTURED SETTLEMENT DESIGN                         │
        │   • Lifetime monthly payments                          │
        │   • Indexed/increasing benefits                        │
        │   • Periodic lump sums for equipment/home mods         │
        │   • Tax‑free, predictable, non‑market‑exposed income   │
        └────────────────────────────────────────────────────────┘
                                   │
                     (Funding stream engineered for LTSS)
                                   │
                                   ▼
        ┌────────────────────────────────────────────────────────┐
        │   SPECIAL NEEDS TRUST (SNT) /                           │
        │   SUPPLEMENTAL NEEDS TRUST (New York)                   │
        │   • Preserves Medicaid/SSI eligibility                  │
        │   • Receives structured payments                        │
        │   • Pays for supplemental supports                      │
        │   • Can contribute annually to ABLE (up to federal cap)│
        │   • Complies with NY EPTL § 7‑1.12                      │
        └────────────────────────────────────────────────────────┘
                                   │
                     (Trustee manages distributions)
                                   │
                     ┌─────────────┴───────────────────────────┐
                     ▼                                         ▼
        ┌────────────────────────────────┐       ┌──────────────────────────────┐
        │   ABLE ACCOUNT (529A)          │       │   LONG‑TERM SERVICES &       │
        │   • Eligibility age now 46     │       │   SUPPORTS (LTSS)            │
        │     (effective Jan 1, 2026)    │       │   • HCBS waiver services     │
        │   • Tax‑free growth            │       │   • Personal care attendants │
        │   • Beneficiary‑controlled     │       │   • Transportation & tech    │
        │   • Ideal for daily expenses   │       │   • Respite & coordination   │
        │   • Receives SNT contributions │       │   • Quality‑of‑life supports │
        └────────────────────────────────┘       └──────────────────────────────┘
                                   │
                                   ▼
                ┌────────────────────────────────────────┐
                │   STABILITY • DIGNITY • CONTINUITY     │
                └────────────────────────────────────────┘

    📌 Sidebar: ABLE Age Expansion (Effective Jan 1, 2026)

    The ABLE Age Adjustment Act expands eligibility from before age 26 to before age 46, effective January 1, 2026. This opens ABLE accounts to millions of adults with later‑onset disabilities — including TBI survivors, accident victims, veterans, and individuals with chronic or degenerative conditions.

    Why it matters: More clients can now integrate Structured Settlement → SNT → ABLE into their LTSS funding strategy.

    LTSS + Settlement Planning: A Framework That Actually Works

    A competent settlement planner doesn’t ask, “How much is the case worth?” They ask:

    • What LTSS services does this person need now?
    • What will they need in 5, 10, 20 years?
    • How will care intensity change?
    • What public benefits are available — and what are the eligibility traps?
    • What funding model ensures continuity of care?

    Then they build a structure that mirrors the LTSS trajectory.

    See: life care planning and settlement planning for disability.

    🐾 A Watchdog’s Take: LTSS Is Where Corners Get Cut

    This is the part of the case where the industry’s shortcuts become unforgivable:

    • “We don’t need a life care plan.”
    • “The family can provide the care.”
    • “Medicaid will cover it.”
    • “Let’s just give them a lump sum.”

    Translation: Let’s shift the risk to the family and hope no one notices.

    See: structured settlement red flags.

    LTSS exposes that tactic instantly. It forces transparency. It forces math. It forces accountability.

    And structured settlements — when designed by someone who actually understands LTSS — force long‑term protection.

    Closing Thought: LTSS Isn’t a Footnote. It’s the Foundation.

    If a settlement involves disability, chronic illness, or aging‑related impairment, LTSS is not optional context. It is the central organizing principle.

    Structured settlements, SNTs, and ABLE accounts — especially with the expanded age eligibility — are the tools that make LTSS sustainable for a lifetime.

    See: structured settlement design for long‑term care.

  • The Corporate Transparency Act: A Transparency Law That Somehow Misses the Opaque

    The Corporate Transparency Act (CTA) was marketed as a crackdown on shell companies, money laundering, and hidden ownership. In practice, it lands squarely on the smallest, most transparent businesses in America — the ones with real offices, real customers, and real names on the door.

    A two‑person LLC that actually makes something must upload passport scans to FinCEN. A local contractor, a family‑owned bakery, a small consulting shop — these are the entities now navigating a federal reporting regime designed for people who hide assets, not people who hang signs.

    Meanwhile, the entities that perfected the art of corporate invisibility — including the multi‑LLC settlement‑purchasing networks that target injury victims — often glide right through the exemptions. A national factoring group with 20+ employees, $5 million in revenue, and a thicket of single‑purpose LLCs? Exempt.

    Beaumont TX and Appellate courts have already confronted this pattern directly, including a case where a Florida‑based factoring entity used a short‑lived LLC and an independent contractor to extract payments from a mentally disabled man — a sequence I documented in FL Company Preyed on Mentally Disabled Man’s Structure and Caused Alleged Loss of Government Benefits – Structured Settlements 4Real®Blog (May 10, 2020).

    The irony is hard to miss: the more complex and opaque the structure, the more likely it is to fall outside the CTA’s reach.

    The Pop‑Up LLC Pattern

    In the settlement‑purchasing world, opacity isn’t a bug — it’s a feature. Transactions are routed through single‑purpose LLCs that appear, transact, and dissolve with minimal traceability. Each LLC is technically “small,” but the network behind them is anything but. The structure allows the enterprise to operate nationally while avoiding the scrutiny that a single, consolidated entity would attract.

    Colorful pastries featuring the letters 'LLC' on them, positioned in a toaster with smoke rising.

    In many jurisdictions, factoring companies monitor court dockets and show up at transfer hearings to gazump a competitor — swooping in at the last minute with a “better offer” to derail the original deal. To prevent this, some enterprises route transactions through disposable LLCs so rivals can’t recognize the petition until it’s too late to interfere. The fragmentation isn’t just about obscuring ownership; it’s also a competitive tactic designed to keep other buyers from poaching the deal before the judge signs off.

    Why These Entities Are Hard to Track

    These LLCs often share:

    • common funding sources.
    • common managers,
    • common addresses,
    • common operating agreements,

    But because each LLC is legally distinct, the CTA treats them as isolated, low‑risk entities — even when they function as arms of a larger, coordinated enterprise. The result is a regulatory blind spot: the very structures designed to obscure ownership are the ones least affected by a law meant to expose it.

    In the end, that’s the real asymmetry: the people who can least afford to lose their protection are the ones matched with companies that never have to stand still long enough to be seen.

  • Incorrigible MJ Settlements Continues Its Daredevil Pattern of Misrepresentation in Facts and Financial Ratings to Investors🪓

    by Structured Settlement Watchdog

    • ⚡MJ Settlements’ website continues to present factored structured settlement receivables as if they were annuity‑like, A‑rated, guaranteed products.
    • 📉The company’s marketing still leans on the tagline “Guaranteed to Outperform” and
    • 🕰️Continues to use the term “SSA” in ways that obscure the true nature of the product and
    • ⚖️Misleads investors about the level of safety, regulation, and protection involved. This pattern of misrepresentation is visible across the company’s website.

    MJ Settlements continues to assert that its receivables are “backed by A‑rated life insurance companies.” Its current listings feature receivables from:

    • Talcott Life Insurance Company
    • Genworth Life insurance Company

    🔄Misrepresentation Through the “SSA” Label

    MJ Settlements continues to describe its offerings as “SSAs,” a term that mimics “structured settlement annuity” but does not transform a receivable into an annuity. These are factoring‑company receivables, not insurance products. Using the abbreviation SSA does not make the representation accurate or exculpatory.

    • However, Genworth does not hold a single A‑level rating from any major rating agency.
    • A.M. Best rating for Genworth Life Insurance Company: C++ (Marginal). Source: Genworth Life Insurance Company website; A.M. Best, March 1, 2026.

    Genworth last held an A‑ rating in 2019, but that rating was withdrawn years ago. A C++ rating is considered “marginal”—far below the A‑level financial strength implied in MJ Settlements’ marketing.

    A review of MJ Settlements’ current inventory shows that every deal being marketed involves payments that do not begin for 10 or more years. These are not short‑duration, near‑term receivables. They are long‑tail obligations, often with first payments scheduled 10, 15, or even 19 years into the future.

    Long deferrals significantly magnify investor risk:

    • Extended credit‑quality exposure to insurers like Genworth, currently rated C++ (Marginal).
    • No interim cash flow, meaning no liquidity or risk offset.
    • Greater vulnerability to future downgrades, restructurings, or insolvency events.
    • No guaranty association protection, because these are not annuities.

    The duration risk is not disclosed with the same emphasis as the marketing claims, creating a mismatch between investor expectations and the actual risk profile.

    None of the receivables marketed by MJ Settlements are eligible for protection under any state life and health insurance guaranty association. These protections apply only to insurance products, such as legitimate structured settlement annuities issued directly to injury victims. Factored receivables — the type MJ Settlements sells — are not insurance, not annuities, and not covered by any insolvency safety net.

    If the underlying insurer fails, restructures, or enters rehabilitation, the investor has no guaranty association protection, no statutory backstop, and no priority status.

    State insurance laws prohibit licensed agents from advertising, referencing, or implying the existence of state guaranty association protection in connection with the sale of any insurance product. These rules exist to prevent agents from using guaranty funds as a substitute for proper disclosure of insurer financial strength.

    This matters because MJ Settlements’ marketing uses annuity‑adjacent language — “SSA,” “A‑rated backing,” “Guaranteed to Outperform” — language that naturally leads an unsophisticated investor to assume the same protections that apply to regulated insurance products.

    But the products being sold are not annuities, not insurance, and not eligible for any insolvency or guaranty scheme. Even if they were insurance products, a licensed agent would still be prohibited from using guaranty‑fund concepts as a marketing tool.

    The result is a presentation that avoids explicitly mentioning guaranty funds but relies on the investor believing the protections exist.

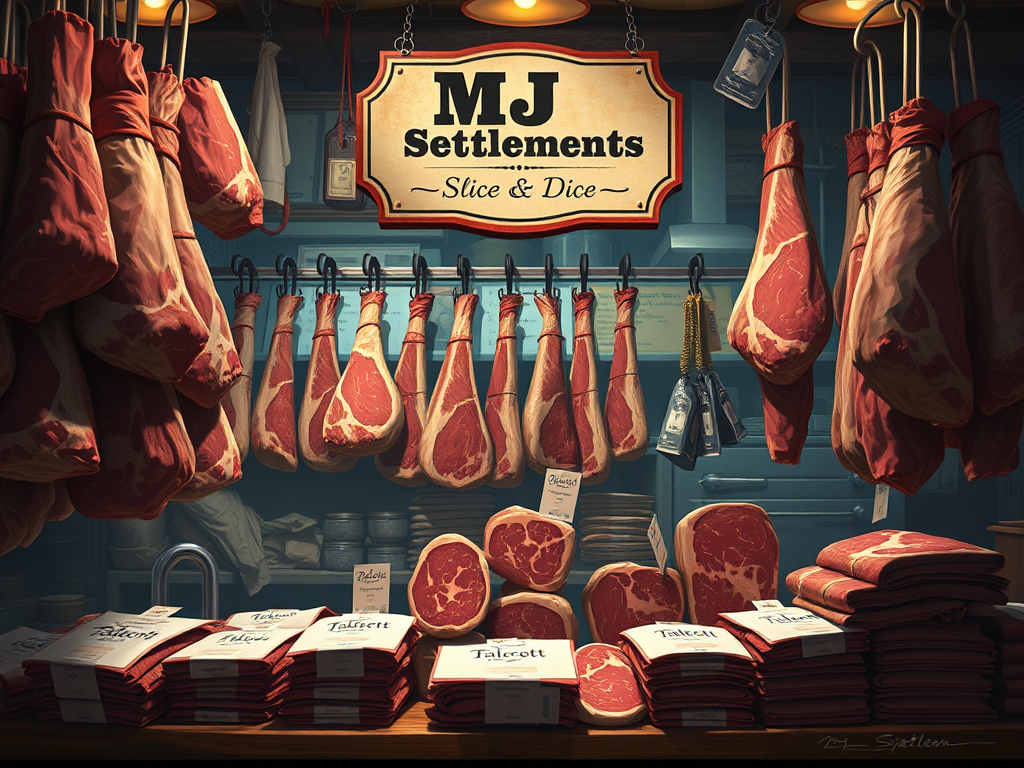
    MJ Settlements continues to present its offerings the way a butcher wraps raw meat: tightly, neatly, and in a way that hides what’s actually inside. The receivables are sliced, bundled, and re‑labeled as “SSAs,” then wrapped in marketing paper that emphasizes “Guaranteed to Outperform” while concealing the underlying credit quality and the extreme deferral periods.

    The metaphor fits because the presentation is clean, but the product underneath is not. The receivables are not annuities, the insurers behind them are not A‑rated, the payment streams are not near‑term, and the risks are not disclosed. Just as butcher paper hides the cut, the marbling, and the freshness of the meat, MJ Settlements’ marketing hides the C++ (Marginal) rating of Genworth and the fact that every current deal involves payments deferred 10 or more years into the future.

    The wrapping is clean. The product is not.

    MJ loves to describe its sliced payment streams as “CD replacements,” a phrase that sounds reassuring until you remember one small detail: certificates of deposit come with FDIC insurance. The butcher’s “daily special” does not.

    A real CD sits inside a federally regulated banking system with explicit, statutory protection up to $250,000 per depositor, per bank. If the bank fails, the FDIC steps in. Your principal is protected by law, not by marketing copy.

    A factored structured‑settlement receivable has none of that.

    • It is not a bank product.
    • It is not insured.
    • It is not guaranteed by the FDIC, a state guaranty association, or any insurer.
    • It is simply a court‑approved assignment of someone else’s future payments, wrapped in butcher paper and sold as if it were a federally protected instrument.

    Calling these receivables “CD replacements” is like calling a butcher’s wrapped ribeye a “replacement for USDA‑inspected packaged beef.” The packaging may be white, but the regulatory protections are not remotely comparable.

    Bucther ship with mears hanging a metaphor for a structured settlement factoring butcher chop shop,Flags are sticking out of the meat identifying the cuts

    🎭“Guaranteed to Outperform” — A Tagline Without Support

    Despite the deteriorated ratings of at least one of the companies behind its receivables and the long‑deferred nature of the payments, MJ Settlements continues to use the tagline:

    “Guaranteed to Outperform.”

    There is no evidence of any guarantee, and no basis for claiming outperformance. When combined with:

    • Misrepresented credit quality
    • Misleading product labeling
    • Deeply deferred payment schedules

    …the result is a marketing presentation that is materially inconsistent with the underlying risk.

  • Co‑Signing Without Signing: The Hidden Credit Traps That Can Derail Settlement Payees

    A recent Moneywise/MSN story about a young woman whose ex‑boyfriend wrecked her credit shows how “co‑signing” happens long before anyone signs a loan. It happens when someone adds you to a lease, a phone plan, a utility account, or a shared credit line because it’s “easier.” The damage is one‑directional: one person can crater the other’s credit profile with missed payments, late fees, or charge‑offs, and the victim has almost no leverage to unwind it.

    Injury victims and structured‑settlement payees live inside a financial ecosystem that most people never see. Their names, payment schedules, and case details circulate through data brokers, list sellers, and “lead generation partners” who treat human vulnerability as an asset class. That means a single credit entanglement — a shared phone plan, a lease, a utility account — doesn’t just expose them to someone else’s financial behavior. It exposes them to an entire industry built to exploit any sign of financial stress.

    When a settlement payee’s credit gets dinged, even slightly, it triggers a predictable chain reaction: more aggressive factoring solicitations, higher‑pressure pitches, and attempts to leverage the victim’s anxiety about their credit score into a quick sale of future payments. The person who caused the damage may walk away, but the payee is left with the fallout — and a target on their back.

    For minors and young adults, the risk is even sharper. They often don’t have long credit histories, so one late payment or charge‑off from someone else’s behavior can distort their entire financial identity. And because their structured settlement is often the only stable asset in their name, predatory actors see them as low‑hanging fruit.

    Most people think co‑signing means sitting in a bank and signing a loan agreement. In reality, the most dangerous forms of co‑signing happen in kitchens, group chats, and “can you help me out for a minute?” moments. These are the informal arrangements that quietly create formal obligations — and they’re the ones that routinely ambush settlement payees.

    • Leases and rental agreements — Being added “just to qualify” makes you jointly responsible for every missed payment, every late fee, and every eviction mark. Landlords don’t care who actually lived there; they care whose credit they can hit.
    • Utility accounts — Gas, electric, water, internet. The person whose name is on the account is the one who gets the collection notice, even if they moved out months ago. Utilities are notorious for reporting charge‑offs that stick for years.
    • Cell phone plans — The modern Trojan horse. One missed payment on a shared plan can tank the credit of the person who agreed to “just put it in my name for now.” Add‑a‑line promotions create long‑term obligations disguised as convenience.
    • Authorized‑user setups — Marketed as a way to “help someone build credit,” but the risk flows only one way. If the primary cardholder racks up debt or pays late, the authorized user inherits the damage without ever touching the card.
    • Joint bank accounts — Not technically credit, but a direct pipeline for overdraft fees, negative balances, and disputes that can spill into ChexSystems and block someone from opening accounts elsewhere.

    Each of these arrangements creates a financial tether that behaves exactly like co‑signing — but without the explicit warning labels. And because settlement payees often want to help family, partners, or friends, they’re more likely to say yes to these “small” requests that carry outsized consequences.

    A young woman in a wheelchair, smiling as she reads documents, while a man in the background stands attentively.

    🎯How Credit Entanglements Become Leverage for Predatory Actors

    Once a settlement payee is tied to someone else’s financial behavior, the vulnerability doesn’t stay private. A late payment, a collections notice, or a sudden dip in a credit score becomes a signal flare in an ecosystem that already treats settlement recipients as targets. Data brokers package these signals. Lead generators resell them. And factoring companies use them as timing cues, reaching out when a payee is most anxious, most stressed, and most likely to make a short‑term decision with long‑term consequences.

    The pitch is always the same: “If you’re behind on bills, we can help you get cash fast.” What they don’t say is that the “help” is built on exploiting the very credit damage someone else caused. A missed utility payment from an ex‑partner becomes the opening line of a sales script. A shared phone plan gone bad becomes justification for a lowball offer. A collections mark becomes a pressure point.

    For minors and young adults, the leverage is even more lopsided. They often don’t understand how these entanglements work, and predatory actors count on that. A single negative mark can make them feel trapped, ashamed, or desperate — all emotions that make them easier to manipulate into selling future payments they were supposed to rely on for stability.

    The danger isn’t just the credit damage itself. It’s the way that damage becomes a tool in someone else’s hands.

    🛡️Recognizing the Early Signs of a Hidden Co‑Signing Trap

    These entanglements rarely announce themselves. They show up as favors, shortcuts, or “temporary” arrangements that quietly become permanent. The earliest warning signs are almost always emotional, not financial. Someone needs you to “just put it in your name,” or they frame the request as a test of trust, loyalty, or commitment. The pressure is subtle: You’re the responsible one. You have better credit. You’re helping us build a future. But the obligation lands squarely on your credit report, not theirs.

    Another early sign is asymmetry. If the other person insists on using your name, your account, or your credit — but never offers theirs — that’s not partnership. That’s risk transfer. And for settlement payees, that risk transfer is amplified because any damage to their credit profile becomes a vulnerability that outsiders can exploit.

    The final red flag is urgency. Predatory dynamics thrive on speed. “We need to do this today.” “The promotion ends tonight.” “The landlord won’t wait.” Urgency is a tactic to bypass your judgment and get you to take on an obligation you wouldn’t accept with a clear head.

    These patterns repeat across leases, utilities, phone plans, and shared credit lines. They’re not coincidences. They’re the behavioral fingerprints of financial entanglement.

    🛡️Protecting Yourself Without Cutting Yourself Off

    Avoiding these traps isn’t about becoming suspicious of everyone around you. It’s about recognizing that financial boundaries are a form of self‑preservation, especially for people whose future stability depends on protecting a structured settlement. The safest protections are simple, consistent, and non‑negotiable. They don’t require confrontation; they require clarity.

    • Your name stays on your accounts, not theirs. If someone needs a lease, a phone plan, or a utility account, it should be in their name. If they can’t qualify, that’s a financial reality — not your responsibility to absorb.
    • No “temporary” arrangements. Anything described as temporary has a way of becoming permanent the moment something goes wrong. If it needs to be temporary, it needs to be in writing, with a clear end date and a clear exit.
    • No shared obligations without shared control. If you can’t see the bill, the balance, or the payment history, you shouldn’t be responsible for it. Transparency is the minimum requirement for shared risk.
    • Document everything that touches your credit. Screenshots, emails, texts — anything that shows who agreed to what. Documentation isn’t about mistrust; it’s about having a record when someone else’s memory becomes selective.
    • Use “no” as a boundary, not a judgment. A firm no protects your credit, your settlement, and your future. People who respect you will respect your boundaries. People who don’t respectyour boundaries shouldn’t have access to your credit.
    • These protections aren’t about being difficult. They’re about refusing to let someone else’s financial behavior become a lever that strangers — including predatory actors — can use against you.

    The Bigger Picture: Why Settlement Payees Are Uniquely Exposed

    • Hidden co‑signing traps don’t exist in a vacuum. They sit inside a larger ecosystem where injury victims and settlement payees are already treated as data points to be tracked, profiled, and monetized. Their payment streams are predictable. Their identities are often public. Their financial histories are thin or disrupted by the injury itself. That combination makes them unusually visible to industries that profit from vulnerability.
    • Credit damage — even when caused by someone else — becomes part of that visibility. A missed utility payment or a collections mark doesn’t just hurt a credit score; it signals instability to the very actors who monitor these patterns. Factoring companies, list brokers, and “financial assistance” marketers don’t need to know the story behind the damage. They only need to know that someone with a future payment stream is under pressure.
    • This is why the stakes are different for settlement payees. A credit entanglement that might be inconvenient for the average person becomes a structural risk for someone whose long‑term financial security depends on protecting a finite, court‑approved income stream. The danger isn’t just the bad credit. It’s the way that bad credit becomes a doorway for outsiders who have every incentive to push the payee into decisions that benefit everyone except the payee.
    • And because these vulnerabilities are relational — rooted in trust, family, romance, or obligation — they’re harder to spot and even harder to talk about. That silence is part of what keeps the cycle going.

    🧩Bringing It Back to the Story — and Why It Matters Now

    The Moneywise/MSN story isn’t unusual. It’s ordinary. That’s what makes it dangerous. A young woman trusted someone, mingled finances in ways that felt harmless, and ended up carrying the full weight of someone else’s decisions. Most people read that and think, “That could never happen to me.” But for settlement payees, the stakes are higher, the exposure is wider, and the consequences travel farther.

    Credit entanglements don’t just damage a score. They distort a financial identity. They create openings for outsiders who profit from instability. They turn private relational dynamics into public vulnerability signals. And they do it quietly, long before anyone realizes what’s been set in motion.

    The real lesson isn’t about the ex‑boyfriend in the article. It’s about the ecosystem that waits downstream from moments like that — the data brokers, the lead sellers, the factoring companies, the opportunists who monitor for signs of stress and move in when someone is most exposed. Settlement payees don’t get the luxury of treating these entanglements as minor mistakes. They’re structural risks with long shadows.

    It lands with the exact snap you want at the end of a piece like this — a single, distilled insight that reframes the entire article in one line.

    If you want to place it visually, it works best right before your final paragraph or as the final line depending on how strong you want the exit to feel.

    Protecting a structured settlement isn’t just about saying no to predatory offers. It’s about recognizing the everyday situations that create the conditions for those offers to appear in the first place. The traps are small. The consequences aren’t.

  • NYC GMVA Look back Window | A Second Chance at Justice: Understanding NYC’s 2026 GMVA Lookback Window and How Settlement Planning Supports Survivors

    by John Darer CLU ChFC MSSC CeFT RSP CLTC

    New York City’s 2026 amendment to the Gender‑Motivated Violence Act (GMVA) marks a major shift in how survivors of gender‑based violence can pursue civil justice. Bill 1297‑A, effective January 29, 2026, opens an 18‑month revival window allowing survivors to bring claims that were previously dismissed or considered too old under prior statutes of limitations.

    This development is not happening in isolation. It sits within a decades‑long legal and cultural evolution—one that has repeatedly expanded, restricted, and re‑expanded survivors’ access to civil remedies.

    This article explains the history behind the GMVA, why the 2026 amendment matters, and how structured settlements and settlement planning can support survivors who choose to pursue civil claims.

    The modern legal framework for gender‑motivated violence began with the Violence Against Women Act (VAWA) of 1994, which included a federal civil cause of action for survivors. Congress intended to treat gender‑based violence as a civil rights violation, not merely a criminal offense.

    In 2000, the U.S. Supreme Court struck down that civil remedy in United States v. Morrison, ruling that Congress lacked constitutional authority to create it. The decision left a vacuum: survivors lost a federal civil rights pathway, and states and municipalities were forced to build their own.

    New York City responded by enacting the Gender‑Motivated Violence Act, a municipal civil rights statute designed to restore what the Supreme Court had removed.

    ⏳The GMVA Before 2026: A Strong Law With Limited Reach

    Although the GMVA created a civil remedy, several structural issues limited its effectiveness:

    • Courts interpreted “gender motivation” narrowly.
    • Strict statutes of limitations cut off older claims.
    • Institutional defendants often escaped liability due to ambiguous statutory language.
    • Procedural dismissals between 2023 and 2025 left many survivors without recourse.

    The result was a law that looked powerful on paper but often failed survivors in practice.

    Jurice as a system craved into balcck garnite in a refklecting pool infront of a majest8c cour
thouse

    🔄The National Revival Window Movement Sets the Stage

    Beginning in the late 2010s, states across the country began passing revival windows—temporary periods allowing survivors to file claims regardless of when the abuse occurred. New York led the movement with the Child Victims Act and Adult Survivors Act, both of which revealed:

    • Survivors often need years or decades to come forward.
    • Institutions frequently used time limits to avoid accountability.

    But these windows did not cover all forms of gender‑motivated violence. Many survivors still had no civil pathway.

    Bill 1297‑A fills that gap.

    🏛️What the 2026 GMVA Amendment Does

    Creates an 18‑Month Revival Window

    Survivors may now file civil claims for gender‑motivated violence that occurred:

    • Years or decades ago
    • Before January 9, 2022
    • Even if previously dismissed on procedural grounds

    This includes cases dismissed between March 1, 2023 and March 1, 2025.

    🧩Expands Liability to Institutions

    The amendment clarifies that survivors may sue:

    • Schools and universities
    • Workplaces and employers
    • Government agencies
    • Shelters and residential programs
    • Healthcare facilities
    • Religious institutions
    • Nonprofits
    • Any entity that enabled, ignored, concealed, or failed to prevent abuse may now be held accountable.

    Restores the GMVA’s Original Purpose

    The GMVA once again functions as a civil rights remedy, not merely a tort statute.

    Why This Window Matters

    The revival window corrects longstanding structural failures:

    • Survivors were told their cases were “too old,” even when institutions caused the delay.
    • Courts dismissed cases on technicalities rather than merits.
    • Institutions often avoided scrutiny through procedural defenses.
    • Gender‑motivated violence was treated as an individual act, not a systemic civil rights issue.

    The amendment acknowledges that the system—not the survivors—was the barrier.

    🔍What Survivors Can Seek Through Civil Litigation

    Under the amended GMVA, survivors may pursue compensation for:

    • Medical care
    • Therapy and mental health treatment
    • Lost income or reduced earning capacity
    • Pain and suffering
    • Emotional distress
    • Long‑term psychological harm
    • Loss of quality of life

    Courts may also award punitive damages in cases involving egregious conduct.

    💠How Structured Settlements and Settlement Planning Support Survivors

    Civil justice is not only about accountability—it is also about long‑term stability. Survivors who obtain compensation often face complex financial, emotional, and practical decisions. This is where structured settlements and settlement planning become essential.

    🛡️Protecting Survivors From Financial Exploitation

    Survivors of trauma are frequently targeted by predatory financial actors. A structured settlement can:

    • Provide guaranteed, tax‑free periodic payments
    • Reduce the risk of rapid dissipation
    • Create long‑term financial security
    • Ensure funds are available for therapy, medical care, and life rebuilding

    Supporting Trauma‑Informed Financial Decision‑Making

    Settlement planning helps survivors:

    • Evaluate lump‑sum vs. structured options
    • Plan for long‑term care and treatment
    • Protect assets from mismanagement or outside pressure
    • Align financial decisions with personal recovery goals

    Coordinating With Attorneys and Advocates

    A settlement planner can work alongside legal counsel to:

    • Model different settlement structures
    • Ensure financial arrangements comply with legal requirements
    • Protect public benefits when necessary
    • Create a plan that supports safety, stability, and autonomy

    Ensuring Survivors Maintain Control

    A well‑designed settlement plan gives survivors:

    • Predictable income
    • Protection from coercion or financial manipulation
    • A financial foundation that supports healing and independence

    Structured settlements are not about limiting choices—they are about protecting survivors’ futures.

    🔍What Comes Next

    The 2026 GMVA revival window will likely reshape NYC litigation for years:

    • Increased filings involving schools, workplaces, shelters, and detention facilities
    • Renewed scrutiny of institutional cover‑ups
    • Expanded case law defining “gender motivation”
    • Constitutional challenges to the revival window
    • Greater coordination between civil and criminal investigations

    Revival windows don’t just reopen old cases—they expose old systems.

    🌉Closing Thoughts

    The 2026 GMVA amendment is part of a broader national reckoning with how the law has historically minimized gender‑based harm. For survivors, it represents a second chance at justice. For institutions, it represents overdue accountability. And for those who support survivors—attorneys, advocates, and settlement planners—it represents an opportunity to help rebuild lives with dignity, stability, and long‑term security.

  • Press Release → Siren Songs → Shipwreck

    On August 26, 2025, Structured Strategy™ issued a press release announcing a new service offering a “bridge to Bitcoin” for structured settlement recipients. It was bold, modern, and delivered with the kind of optimism that makes you lean in a little. You could almost hear the ancient Greek Sirens warming up — not maliciously, just confidently singing about the future.[1]

    And to be fair, the idea does have a certain mythic charm. A bridge. A frontier. A chance to turn tomorrow’s payments into today’s opportunity.

    But ideas and outcomes don’t always travel the same road.

    If You Acted on the Press Release That Day

    Let’s imagine someone read that press release on August 26, 2025, felt inspired, and decided to follow the melody. They sold their structured settlement payments — likely at pennies on the dollar[5] — and used the proceeds to buy one of the crypto‑linked assets that often ride shotgun with Bitcoin’s narrative.

    Fast‑forward to February 24, 2026. Here’s where they’d be:

    AssetAug 26, 2025Feb 24, 2026Change
    Bitcoin (BTC)$111,802.66$64,080.04–42.7%
    IBIT$63.10$36.53–42.1%
    Strategy (MSTR)$351.36$124.61–64.5%

    [2]

    Now to be fair:

    Someone could have entered or exited anywhere along the way. Crypto is a wide ocean, and there are always moments when the waves rise and fall. This isn’t about catching the exact top or bottom — it’s simply a snapshot of what the journey would have looked like if you stepped onto the bridge the day the press release came out and held on until now.

    And that journey, for most people, would have been… bumpy.

    The Double‑Loss Problem (Sung Softly)

    The first loss happens quietly: selling guaranteed structured settlement payments at a discount. That’s the price of admission.

    The second loss is louder: discovering that Bitcoin and its cousins don’t glide — they plunge, soar, twist, and dive. A 40–60% drawdown isn’t a crisis in crypto; it’s character development.

    And if someone panics and sells during the drop, they may discover a third surprise waiting for them at tax time: short‑term capital losses[4]. When you sell an asset held for less than a year, the IRS treats it as short‑term — netted against short‑term gains and taxed at ordinary income rates. Not catastrophic, but certainly not the “future‑forward opportunity” the Sirens were singing about.

    Most people aren’t built for that kind of ride. They feel the regret early. They bail. They lock in the loss — and sometimes the tax treatment too.

    Not because they’re weak — because they’re human.

    📘 Sidebar Explainer: Short‑Term vs. Long‑Term Capital Gains

    Short‑Term Capital Gains (Held ≤ 1 year)

    • Taxed at ordinary income rates
    • Offset only against short‑term losses
    • Often higher tax impact
    • Common when someone panics and sells during volatility

    Long‑Term Capital Gains (Held > 1 year)

    • Taxed at preferential rates
    • More favorable treatment
    • Requires staying invested through the ups and downs

    Why This Matters Here

    If someone sold structured settlement payments to buy crypto and then bailed during a downturn, they didn’t just lock in a financial loss — they likely locked in a short‑term one. That’s the tax equivalent of saltwater in the wound.

    The Siren Song, Revisited

    The Sirens in Greek mythology weren’t dangerous because they were evil. They were dangerous because their song was beautiful.

    The same is true here. The idea of turning structured payments into crypto gains is alluring. It’s modern. It’s exciting. It’s easy to imagine the upside.

    But the emotional physics of volatility are unforgiving, and most people don’t have the rope and mast that Odysseus used to stay the course.[7]

    A stone monument with the text 'Cash Now to Crypto' surrounded by water, with a boat named 'THE STRUTURE' in the background.

    ✨ Moral of the Story

    At the end of the day, the idea of swapping guaranteed income for a ride on the crypto roller coaster has a certain sparkle to it — the kind of thing that sounds great in a press release and even better over coffee. But sparkle isn’t stability, and volatility isn’t a settlement plan, or a retirement plan.

    It’s not that anyone meant harm.

    ✍️ Closing Author’s Note

    Structured settlements exist for a reason: to provide long‑term financial stability for people who need it most. The laws around selling those payments — the court approval, the waiting periods, the independent advice — aren’t obstacles. They’re guardrails.

    They’re there to make sure that when a new idea comes along, no matter how shiny or melodic, people have time to think, breathe, and decide with clarity rather than impulse.

    Innovation is welcome.

    Opportunity is welcome.

    📜Authenticity Note

    You can’t simply “sell your structured settlement payments” the way you’d pawn a guitar. Every state has a Structured Settlement Protection Act, and any sale of future payments requires independent professional advice in some states and a judge’s approval in all states. The process typically takes 60–90 days, sometimes longer.

    Even if someone wanted to act on a press release the same day it came out, the law builds in a cooling‑off period — a safeguard designed to protect people from exactly the kind of impulsive, Siren‑song decisions that volatility (and short‑term tax consequences) can turn into regret.

    ⭐Footnotes

    [1] BusinessWire. “New Service from Structured Strategy™ Targets $100 Billion Structured Settlement Market with a Bridge to Bitcoin.” August 26, 2025.

    [2] Publicly available market pricing for Bitcoin (BTC), IBIT, and MicroStrategy (MSTR) on August 26, 2025 and February 24, 2026.

    [3] Structured settlement payment transfers require court approval under each state’s Structured Settlement Protection Act (SSPA). Typical timelines range from 60–90 days depending on jurisdiction.

    [4] IRS Publication 550: Investment Income and Expenses — short‑term capital gains and losses are taxed at ordinary income rates.

    [5] Discount rates (“pennies on the dollar”) vary based on payment timing, market conditions, and transaction costs in the structured settlement secondary market.

    [6] NASP (National Association of Settlement Purchasers) industry data on discount rate ranges and transfer practices.

    [7] Historical volatility metrics for Bitcoin and related crypto assets show that 40–60% drawdowns within 12‑month windows are common.

    [8] Several states require Independent Professional Advice (IPA) to ensure payees understand the financial implications of selling future payments.