Structured settlements expert John Darer reviews the latest structured settlements and settlement planning information and news, and provides expert opinion and highly regarded commentary. that is spicy, Informative, irreverent and effective for over 20 years.
The STRUCTURED SETTLEMENTS 4REAL® Blog is a highly regarded source for structured settlement news, information, and commentary, led by structured settlement and settlement planning subect mater expert John Darer CLU ChFC MSSC CeFT RSP CLTC. With two decades of operation, the blog and 4structures.com are recognized as comprehensive resources, offering detailed guides and specialized insights. Established in 2005, the blog caters to a broad audience, including legal professionals, injured individuals, families, and various stakeholders, providing reviews and opinions on settlement planning. John Darer, President of 4structures.com LLC, is a seasoned structured settlement expert with over 40 years of financial services experience and 31 years specializing in structured settlements. Based in Stamford, CT, he is a Certified Financial Transitionist and Registered Settlement Planner, holding insurance licenses in 45 states and the District of Columbia. John Darer is dedicated to transparency and advocacy, he emphasizes the importance of engaging trained and licensed professionals for settlement planning, offering valuable insights through his investigative journalism and professional commentary.
SDNY confirms Wander used fraudulently obtained funds to invest in soccer teams and aircraft, among other ventures . This aligns directly with reporting on 777’s liquidity drain and the structured‑settlement vertical being used as a cash engine.
🔥2. The Double‑Pledging Is No Longer Allegation — It’s Admitted Conduct
The DOJ release explicitly states Wander pledged assets to multiple lenders and misrepresented collateral positions . This validates the “Ghost Assets” and “Double‑Pledging” series — and gives prosecutorial confirmation for every forensic breadcrumb laid out.
🔥3. Altered Bank Statements Are Confirmed
The DOJ notes Wander provided altered bank statements to lenders to inflate cash balances and secure financing . This is the exact pattern identified in SuttonPark’s servicing irregularities and lender reconciliation failures.
🔥4. The Soccer‑Club Angle Is Now Part of the Official Narrative⚽
AP News and other outlets confirm that fraudulently obtained funds were used to invest in European soccer clubs, many of which struggled under 777 ownership . This ties neatly into the Everton/Genoa coverage and the broader “sports‑washing via structured‑settlement cashflow” theme.
🔥5. The Collapse Timeline Is Now Locked
The plea confirms the chronology:
Fraud active through 2021–2023
Double‑pledging discovered March 2023
Wander resigns May 2024
SEC civil case 2025
Guilty plea October 2026
Sentencing March 2027
Every major milestone is now backed by federal filings and mainstream reporting.
🔥6.Altered Bank Statements
Wander admitted that 777 Partners provided lenders with bank statements that were altered to inflate cash balances and conceal shortfalls. These manipulated documents were used to secure financing, maintain credit lines, and reassure counterparties who were already questioning the firm’s liquidity. With the guilty plea, the doctored statements move from suspicion to established fact.
With Wander’s guilty plea now on the record, the SuttonPark/777 disaster is no longer a mystery, nor a matter of competing narratives. The structured‑settlement servicing collapse, the lender disputes, the ghost assets, the contradictory payee communications — all of it traces back to a single, sprawling fraud that prosecutors say bilked lenders and investors out of more than half a billion dollars. Wander’s admission, his agreement to forfeit at least $500 million, and his upcoming sentencing before Judge J. Paul Oetken mark the moment when speculation gives way to accountability. For payees, lenders, regulators, and the industry at large, the plea provides clarity: the chaos was not operational failure — it was fraud, and the structured‑settlement business was one of the places where that fraud was concealed.
🔥Wander’s run of luck may finally have hit the wall — and it’s been running a long time✈️
Two decades before pleading guilty to a half‑billion‑dollar fraud, Wander was a confused, frightened‑looking kid hauled in by Miami police after opening a package containing 31 grams of cocaine. A crime that could have carried 20‑plus years somehow resulted in 16 years of probation after he pled no contest. It didn’t dent his career; he went on to graduate from the University of Florida and build the sprawling financial empire that would later collapse under the weight of lawsuits, repossessions, regulatory downgrades, and now a federal fraud plea. The kid who once dodged a cocaine sentence has finally run out of runway.
A satirical rendering of a Joshua Wander airplane sits damaged against a runway barrier as emergency crews respond nearby.
There’s a recurring practice in the structured‑settlement secondary market that deserves far more scrutiny: steering. Not advising. Not planning. Not licensed guidance. Just steering — nudging someone to sell a stable, court‑ordered income stream and then pointing them toward something riskier, without the credentials or oversight that such influence requires.
For people who rely on structured settlements, that “nudge” is not harmless. It’s the moment the parachute straps get cut.
Structured Settlements Are Designed for Stability
Structured settlements exist because the recipient cannot afford volatility. They cannot afford market swings, speculative products, or “opportunities” that depend on timing and luck. Their stability is intentional. It’s protective. It’s the financial equivalent of a parachute packed by statute, court review, and long‑term planning.
When someone without the proper license initiates the sale of that stability — and then steers the consumer toward a different financial product — they’re not just “helping.” They’re performing the core functions of a financial adviser or broker‑dealer without the legal authority to do so.
Influence Is What Triggers Regulation
Regulators don’t care whether the person signs the paperwork. They care whether the person influenced the decision.
A colorful “Broker Raton” storefront advertises cash loans, cryptocurrency, and penny pyramids amid busy street life.
Influence is what triggers licensure. Influence is what triggers fiduciary duties. Influence is what triggers consumer‑protection laws.
And influence is exactly what steering is.
The Law Cares About the Effect, Not the Choreography
Walking someone “down the street” to another product doesn’t avoid regulation. It doesn’t avoid responsibility. It doesn’t avoid scrutiny.
The law cares about the effect on the consumer, not the choreography of the sales pitch.
For recipients who depend on guaranteed income, steering is not guidance. It’s not education. It’s not empowerment. It’s harm.
Time for a Wake‑Up Call
An extremely loud alarm clock jolts a reluctant shark’s “ampullae di arancini” awake before an early rise, or was it a Sicilian appetizer he had at the marine biology conference last night?
And NOW, for something completely different…
People who engage in this behavior need to recognize exactly what they’re doing. If you initiate the sale of a structured settlement — a regulated financial asset — and then direct the consumer toward another financial product, you are operating in a zone where licensure, fiduciary duties, and consumer‑protection laws apply.
No exceptions. No loopholes. No “I didn’t sign anything” defense.
Steering is influence. Influence is regulated. And consumers deserve better.
What Steering Looks Like
Giving such advice while uninsured, leaving the consumer exposed and the adviser outside regulatory boundaries
Acting on financial direction from someone who is unlicensed and not credentialed, especially when they’re encouraging the sale of a risk‑free or low‑risk asset and steering the consumer into something riskier without adequate disclosures or legally measurable standards
Nudging a consumer to sell guaranteed payments without being licensed to give financial advice
Suggesting or “recommending” a specific buyer, product, or outcome without proper credentials
Presenting a risky alternative as if it were equivalent to a court‑ordered, guaranteed income stream
Initiating the sale of a structured settlement and then directing the consumer toward another financial product
Using familiarity or convenience as a substitute for regulated guidance
Framing the steering as “helping,” “educating,” or “just pointing them in the right direction”
If they’re that careless with their own risk management, what makes you think they’ll pay adequate attention to yours?.
Closing
Steering doesn’t become legitimate just because the person doing it avoids certain words. You can call it “helping,” “educating,” or “sharing an opportunity,” but the moment you start talking about a replacement investment — especially one that carries more risk than the court‑ordered income stream you’re encouraging someone to sell — you’ve crossed into territory where licensure, disclosures, and measurable standards are mandatory.
The problem is that regulation hasn’t caught up with the behavior. Most of the people who steer consumers out of structured settlements have never had securities training, never had to meet suitability standards, and never had to comply with the oversight that governs actual financial professionals.
And in the few states that even require registration for structured‑settlement transfers, the bar is laughably low: no insurance requirement, just a de minimis bond. A bond so small it wouldn’t cover a single consumer’s losses, let alone systemic harm.
So here’s the part consumers need to think about:
If someone is willing to give financial direction while uninsured, unlicensed, uncredentialed, and untrained — what does that say about how they manage their own risk?
If they’re that careless with their own risk management, what makes you think they’ll pay adequate attention to yours — or they’re a predator by nature, or both.
Structured‑settlement recipients deserve better than off‑the‑cuff influence masquerading as guidance. They deserve professionals who understand that moving someone from a guaranteed asset into risk isn’t a casual conversation — it’s regulated conduct.
The wake‑up call is overdue. If you influence the sale of a structured settlement, you step into a regulated world. Act like it.
The following websites currently use the inaccurate term “secondary market annuity” in public‑facing materials, marketing, or SEO content. This list is strictly alphabetical. Each entry includes a citation showing where the term is still being used and the date retrieved.
AnnuityExpertAdvice(Shawn Plummer)
Where they still use it (retrieved October 15, 2026):
Exact phrase “secondary market annuity” used as a product descriptor
SEO headings and meta descriptions containing the term
Marketing copy presenting SMA terminology as if it were correct
No corrective language indicating the product is not an annuity
Branding positions the site as an “annuity expert” while using misleading terminology
Annuity.org
Where they still use it (retrieved October 15, 2026):
Page title: “Secondary Market Annuities: What You Need to Know”
URL slug: /secondary-market-annuities/
Meta description contains exact phrase: “secondary market annuity”
On‑page H1: “Secondary Market Annuities”
MJ Settlements(Todd Michael Lesk)
Where they still use it (retrieved October 15, 2026):
Buyer’s Guide page titled “Buyer’s Guide to Secondary Market Annuities”
On‑page header: “Secondary Market Annuity Income”
Multiple pages using exact phrase “secondary market annuity” as a product descriptor
SEO headings and meta descriptions containing the term
Site tagline uses variant: “Secondary‑Market Reassignment”, which conflicts with the use of the term annuity because structured settlement annuities are not owned by payees/annuitants and cannot be reassigned by payees/annuitants
Marketing copy referencing “secondary market annuity income streams”
Branding positions the company as a structured settlement expert while using misleading terminology
SMA Hub
Where still used (retrieved October 15, 2026):
Homepage hero text includes: “Secondary Market Annuities”
PDF brochures containing exact phrase: “secondary market annuity”
SEO landing pages optimized for “secondary market annuity”
Why the Term Is Incorrect
The phrase “secondary market annuity” has no legitimacy under any state’s annuity statute. Factored structured settlement payment rights are not annuity contracts, and no annuity is being sold, transferred, or purchased in these transactions.
A Non‑Qualified Assignment (NQA) is a settlement mechanism that allows a defendant to transfer its obligation to make future periodic payments in a settlement (or a portion of it) that does not meet the requirements of IRC §130. Because the underlying claim is not a personal physical injury or physical sickness under IRC §104(a)(2), the assignment company does not receive the tax‑free treatment available through a Qualified Assignment.
Upon accepting the transferred obligation, the assignment company assumes full liability for the future periodic payments and funds those obligations using instruments permitted under applicable tax and regulatory frameworks. For private defendants, permissible funding methods include:
Structured settlement annuities
Funding Agreements
Market‑based alternatives, including programs issued through Barbados International Business Companies (IBCs) that rely on Article 11 of the U.S.–Barbados Tax Treaty (Convention of 1984, as amended by the 1991 Protocol), operate under the oversight of a Board of Directors, and comply with AML/KYC requirements
If U.S. Treasury obligations are the desired funding instrument—whether selected for their exceptional safety or required in a taxable case—the periodic payments are funded through Treasuries, which must be placed through a Non‑Qualified Assignment using an offshore assignment company. This structure is required because a U.S.‑domiciled assignee would otherwise be taxed on the interest earned on the Treasuries, undermining the economics of the long‑term payment obligation.
Regardless of the funding method, an NQA provides a customizable, tax‑efficient payment schedule for the claimant while giving the defendant a complete transfer of its long‑term obligation.
⭐2. Why Non‑Qualified Assignments Exist
NQAs are used when:
A. The underlying claim is taxable, such as:
employment claims
discrimination claims
harassment claims
commercial disputes
punitive damages
non‑physical torts
B. The underlying claim is tax‑free but not §130‑eligible, such as:
wrongful imprisonment compensation under IRC §139F
NQAs allow:
defendants and/or their insurers to transfer long‑term payment obligations
claimants to receive structured payments instead of lump sums
states and public entities to resolve obligations cleanly
planners to design predictable, stable financial outcomes
⭐3. Special Case: Wrongful Imprisonment (§139F)
Wrongful imprisonment compensation under IRC §139F is tax‑free to the claimant, but not eligible for a Qualified Assignment because it is not a personal physical injury under §104(a)(2).
This creates a unique combination:
Tax‑free payments to the claimant
Non‑Qualified Assignment mechanics
No §130 safe harbor
Full flexibility in funding instruments
No constructive receipt issues when properly drafted
Even though §139F payments are excluded from income, the structure must be implemented through a Non‑Qualified Assignment, making §139F one of the most important modern use‑cases for NQAs.
⭐4. Funding Options for Non‑Qualified Assignments
NQAs can be funded using four distinct categories of instruments:
Structured settlement annuities
Funding Agreements
Offshore options U.S. Treasury obligations and Market Based Structured Settlement Options (See Section D)
A. Structured Settlement Annuities
Structured settlement annuities can be used in NQAs, but they are subject to IRC §72(u) because the assignment company is a non‑natural person.
Exact statutory language: IRC §72(u)(4)
“Paragraph (1) shall not apply to any annuity contract which is an immediate annuity contract or a contract under which annuity payments have begun (and which provides for substantially equal periodic payments to be made not less frequently than annually) as of the date of purchase.”
What this means
Unless the annuity is immediate, or
unless it begins substantially equal periodic payments within 12 months,
the annuity is treated as if payments had already begun, and the assignment company must begin recognizing income accordingly.
Important: §72(u)(4) limits how long the assignment company may defer the start of annuity payments (maximum 12 months), but it does not limit how long the annuity may pay out once payments have begun. The duration of the payout schedule is unrestricted; only the deferral period is capped.
Result
§72(u)(4) does not eliminate tax deferral,
but it limits deferral to 12 months unless substantially equal periodic payments begin.
Because the assignment company’s liability schedule often extends far beyond 12 months, structured settlement annuities are generally tax‑inefficient for NQAs.
B. Funding Agreements (Preferred for NQAs)
Funding Agreements are not annuities. They are deposit‑type institutional contracts issued by life insurers.
Why they matter
Funding Agreements:
are NOT subject to IRC §72(u)(4)
do NOT have the 12‑month substantially‑equal‑payments requirement
allow the assignment company to match income recognition to liability
provide predictable, non‑life‑contingent cash flows
are backed by the insurer’s general account
are priced institutionally
work for both taxable claims and §139F wrongful‑imprisonment claims
The key doctrinal point
Before Funding Agreements existed, the only way to avoid §72(u)(4) was to go offshore.
Funding Agreements provide a domestic solution for NQAs.
They are not yet the dominant choice, but they are increasingly the economically rational choice for many NQA structures because they avoid §72(u)(4) without requiring offshore assignment.
They may also be the most effective solution for shorter‑duration payment streams for both plaintiffs and attorney fee structures, where the assignment company’s liability schedule aligns naturally with the predictable, non‑life‑contingent cash flows a Funding Agreement provides.
C. U.S. Treasury Obligations
The assignment company funds the periodic payments using U.S. Treasury obligations, one of the available options for satisfying long‑term periodic payment liabilities in taxable cases involving plaintiffs, state defendants, government defendants, and private defendants.
Why Treasuries work
Treasuries:
are not annuities
are not subject to IRC §72(u)(4)
provide high credit quality
offer predictable fixed‑payment schedules
can be structured to match periodic payment obligations
are often cost‑efficient for shorter‑duration solutions
are fully domestic and regulatorily simple
Treasuries are particularly effective for:
fixed‑payment schedules
shorter‑duration payout periods
situations where insurer pricing is less competitive
plaintiffs and private, state or government defendants who prefer government‑backed instruments
Treasuries are a valid and often efficient NQA funding option.
D. Offshore Options
Historically used before Funding Agreements, offshore arrangements may involve:
Some attorneys prefer arrangements where their financial adviser can remain involved in the claimant’s broader financial planning. This preference contributed to the long‑standing use of market‑based structured settlement options, although such preferences can introduce control considerations that make these options case‑specific rather than standard.
Why offshore was used
Offshore assignment companies were not subject to IRC §72(u)(4). This allowed full deferral without the 12‑month substantially‑equal‑payments limitation.
Today
Offshore options still exist, but:
regulatory complexity is higher
jurisdictional risk exists
compliance requirements are significant
Funding Agreements now solve the §72(u)(4) problem domestically for fixed‑payment stream options (MetLife and American General). U.S. Treasury obligations provide another domestic fixed‑payment alternative.
Result
Offshore arrangements have been largely replaced for:
fixed‑payment payout schedules, and
cost‑efficient shorter‑duration solutions,
where domestic Funding Agreements and Treasury obligations offer superior pricing, regulatory simplicity, and administrative efficiency.
Offshore is now case‑specific, not standard.
⭐5. Tax Treatment
Assignment Company
No §130 exclusion
If a domestic annuity is used, IRC §72(u)(4) applies, which requires substantially equal periodic payments to begin within 12 months of purchase.
If using a Funding Agreement: §72(u)(4) avoided, domestic solution
Offshore options: jurisdiction‑specific tax rules
Liability and asset are matched economically
Claimant
Payments are taxable for most NQA cases
Payments are income tax‑free for §139F wrongful incarceration cases
Tax character follows the underlying claim
Regardless of the method, the NQA provides a tax‑efficient, customizable schedule for the claimant.
⭐6. Comparison: Qualified vs. Non‑Qualified vs. §139F
Feature
Qualified Assignment
Non‑Qualified Assignment
§139F Wrongful Imprisonment
Governing statute
IRC §130
None (general tax rules)
IRC §139F
Underlying claim
Physical injury (§104(a)(2))
Taxable claims
Wrongful incarceration
Assignment company tax
Tax exclusion under IRC §130
Tax treatment depends on funding method (domestic vs. offshore); no exclusion under IRC §130 for NQAs
Taxable; no exclusion under IRC §130
Claimant tax
Tax‑exclusion
Taxable
Tax-exclusion
Funding
Annuity or Treasury
Annuity, Funding Agreement, Treasury, Offshore
Funding Agreement ideal
§72(u)(4) issues
No
Yes (if annuity)
Avoided with Funding Agreement or Treasury
⭐7. Regulatory Context
NQAs are governed by:
general tax principles
state insurance regulation
contract law
insurer solvency requirements
settlement agreement terms
terms of the NQA
There is no statutory safe harbor comparable to §130.
⭐8. Advantages of NQAs
allow structured payments for taxable claims
NQAs allow structured payments for any tax‑excluded claim that cannot use §130 because it does not fall under §104(a)(1) or §104(a)(2). For example IRC 139F wrongful incarceration claims
enable defendants to transfer obligations
provide long‑term financial stability
support flexible payment design
Funding Agreements solve §72(u)(4) domestically
Treasuries provide fixed‑payment and short‑duration efficiency
A Non‑Qualified Assignment is the transfer of periodic payment obligations in settlements that do not qualify under IRC §130. NQAs can be funded with structured settlement annuities, funding agreements, U.S. Treasuries, or offshore options, with Funding Agreements and Treasuries being the preferred domestic vehicles because they avoid IRC §72(u)(4). NQAs are essential for taxable claims and for §139F wrongful‑imprisonment claims, where payments are tax‑free to the claimant but still require non‑qualified mechanics. Regardless of the method, the NQA provides a tax‑efficient, customizable payment schedule for the claimant.
Footnote: The favorable tax treatment for Barbados International Business Companies (IBCs) derives from Article 11 of the Convention Between the United States of America and Barbados for the Avoidance of Double Taxation and the Prevention of Fiscal Evasion with Respect to Taxes on Income (1984), as amended by the 1991 Protocol, which exempts qualifying IBCs from U.S. tax on interest income, including interest from U.S. Treasury obligations.
A: A Non‑Qualified Assignment transfers a defendant’s obligation to make future periodic payments in settlements that do not qualify under IRC §130. It is used for taxable claims and §139F wrongful‑imprisonment compensation.
Q: Why would someone use a Non‑Qualified Assignment?
A: NQAs allow defendants to transfer long‑term payment obligations and allow claimants to receive structured, customizable periodic payments when a Qualified Assignment is not permitted.
Q: What types of claims can use a Non‑Qualified Assignment?
A: NQAs are used for taxable claims such as employment, discrimination, harassment, commercial disputes, and punitive damages, as well as tax‑free wrongful‑imprisonment claims under IRC §139F.
Q: What funding instruments can be used for a Non‑Qualified Assignment?
A: NQAs may be funded with structured settlement annuities, funding agreements, U.S. Treasury obligations, or offshore options.
Q: How does IRC §72(u)(4) affect structured settlement annuities in NQAs?
A: IRC §72(u)(4) requires annuities owned by non‑natural persons to begin substantially equal periodic payments within 12 months, limiting deferral for the assignment company.
Q: Why are funding agreements commonly used for NQAs?
A: Funding agreements are not annuities and are not subject to IRC §72(u)(4). They allow the assignment company to match income to liability without the 12‑month substantially‑equal‑payments requirement.
Q: Can U.S. Treasuries be used to fund a Non‑Qualified Assignment?
A: Yes. Treasuries are not subject to IRC §72(u)(4), provide high credit quality, and are often cost‑efficient for fixed‑payment and shorter‑duration schedules.
Q: Are offshore options still used for Non‑Qualified Assignments?
A: Offshore options exist but are now used mainly for specialized cases. They have largely been replaced by annuities fro fixed payments, domestic funding agreements for deferred fixed‑payments and cost‑efficient shorter‑duration solutions.
Q: Are payments to the claimant taxable in an NQA?
A: Payments are taxable unless the underlying claim is tax‑exempt, such as wrongful‑imprisonment compensation under IRC §139F.
Q: Do NQAs allow customized payment schedules?
A: Yes. Regardless of the funding method, NQAs allow fully customizable periodic payment schedules tailored to the claimant’s needs.
A stability roadmap for young adults stepping into adulthood — and into long‑term financial decisions.
🧭 INTRODUCTION: The Moment You Turn 18
Turning 18 is a legal milestone. It’s also a financial one.
If you have a structured settlement, this is the moment you become legally able to sell your payments. If you’re negotiating a settlement, this is the moment you’re deciding whether to take guaranteed income or a lump sum.
This guide exists for one reason:
To help young adults make decisions that protect their future, not sabotage it.
No lectures. No scare tactics. Just clarity.
1️⃣ WHAT A STRUCTURED SETTLEMENTIS— AND WHY IT MATTERS AT 18–25
A structured settlement is guaranteed money paid over time. It’s designed to give you:
stability
predictability
protection
breathing room
long‑term support
It’s not an investment. It’s not a lottery. It’s not a windfall.
It’s a financial stabilizer — the same concept InsuranceNewsNet calls a portfolio stabilizer — but applied to real life, not Wall Street.
You can call this stabilizing layer a:
Volatility Buffer — protects you from chaos
Availability Buffer — gives you accessible, predictable money when you need it
These buffers matter most when you’re young, inexperienced, and possibly facing adult responsibilities for the first time.
2️⃣ TURNING 18 WITH A STRUCTURED SETTLEMENT: WHAT CHANGES
✔ You become legally able to sell payments
Factoring companies know this. They target you aggressively. Some very aggressively.
✔ You start facing adult expenses
Rent, groceries, transportation, phone bills, emergencies — they hit fast.
✔ Your financial experience is not fully formed yet
Not your fault. Nobody teaches this in school.
✔ You’re emotionally vulnerable
Whether you lost a parent, suffered an injury, or just feel overwhelmed — it’s possible that adulthood arrives before the financial literacy does.
This combination makes 18‑year‑olds the #1 target for predatory buyout offers.
3️⃣ THE SELLING TRAP (“SELLOOOO”) — HOW IT WORKS
Factoring companies use:
fake checks
fake approach claiming tio be calling “from the courts” or the insurer
fake need to register in an any kidn of structured settlement registry
AI generated content sludge
“urgent” mailers
social media ads
texts
DMs
“You’re approved!” letters
pressure tactics
emotional manipulation
tell you not to disclose a medical condition or the judge will not approve
structured settlement to crypto approach
They want you to trade long‑term stability for short‑term cash.
They know you don’t understand:
discount rates
present value
long‑term income needs
the permanence of selling payments
You’ve heard about crypto and it sounds cool but you dont know what FOMO and FORO are
They know you’re stressed. They know you’re young. They know you’re legally allowed to sign.
That’s why they target you.
4️⃣ WHY YOUNG ADULTS SELL — AND WHY IT’S A BAD TRADE
Short‑term pressure
Rent due. Groceries needed. Car broke down. Credit card maxed.
Short‑term emotion
Stress. Fear. Grief. Overwhelm. Desire for relief.
Short‑term thinking
“I’ll just sell a few payments.” “I’ll figure out the future later.” “I need money now.”
But selling payments is permanent. You don’t get them back. You lose the stabilizer your future self will depend on.
5️⃣ THE MEANING OF THE MONEY (WITHOUT MAKING IT THE CENTERPIECE)
For some young adults — especially those who lost a parent — the money may carry emotional meaning:
It feels like protection.
It feels like legacy.
It feels like the last structured support a parent left behind.
This doesn’t make the guide trauma‑centered. It simply acknowledges reality:
When money has meaning, decisions may feel heavier — and mistakes hurt more.
Your volatility buffer protects young adults from making irreversible decisions during emotionally volatile years.
6️⃣ IF YOU’RE 18–25 AND DECIDING WHETHER TO TAKE A STRUCTURED SETTLEMENT
Here’s the truth:
✔ Lump sums disappear fast
Cars, rent, lifestyle creep, friends, impulsive spending, bad investments.
✔ Structured settlements protect you from yourself
Not because you’re irresponsible — because you’re human.
✔ A good structured settlement for young adults includes:
immediate cash for real needs
monthly income for stability
lump sums timed for school, training, medical needs, emergencies
long‑term payments that protect future you
a volatility buffer that absorbs life’s chaos
This is how you build stability at an age when life is anything but stable.
7️⃣ THE CORE MESSAGE OF THE GUIDE
You don’t need to be perfect. You don’t need to know everything. You don’t need to make every decision alone.
But you do need to understand this:
Your structured settlement is designed to protect your future self — especially when your present self is overwhelmed.
Selling it removes that protection. Not taking one forfeits it.
8️⃣ THE CHECKLIST: READ THIS BEFORE YOU SELL ANYTHING
Do I understand my payment schedule?
Do I know the real value of what I’m being offered?
Am I making this decision under stress?
Am I being pressured?
Am I thinking about today instead of tomorrow?
Am I about to give up stability for a short‑term fix?
Have I talked to someone who isn’t getting a commission?
If any answer is “no,” pause.
Your future self will thank you.
9️⃣ THE CLOSING NOTE
This guide isn’t about fear. It’s about clarity.
It’s about giving young adults the tools to make decisions that protect their future — not sabotage it.
It’s about explaining structured settlements in a way that’s modern, human, and honest.
It’s about giving them the language to understand:
“I’m not stupid — I’m overwhelmed.And this money is meant to protect me.”
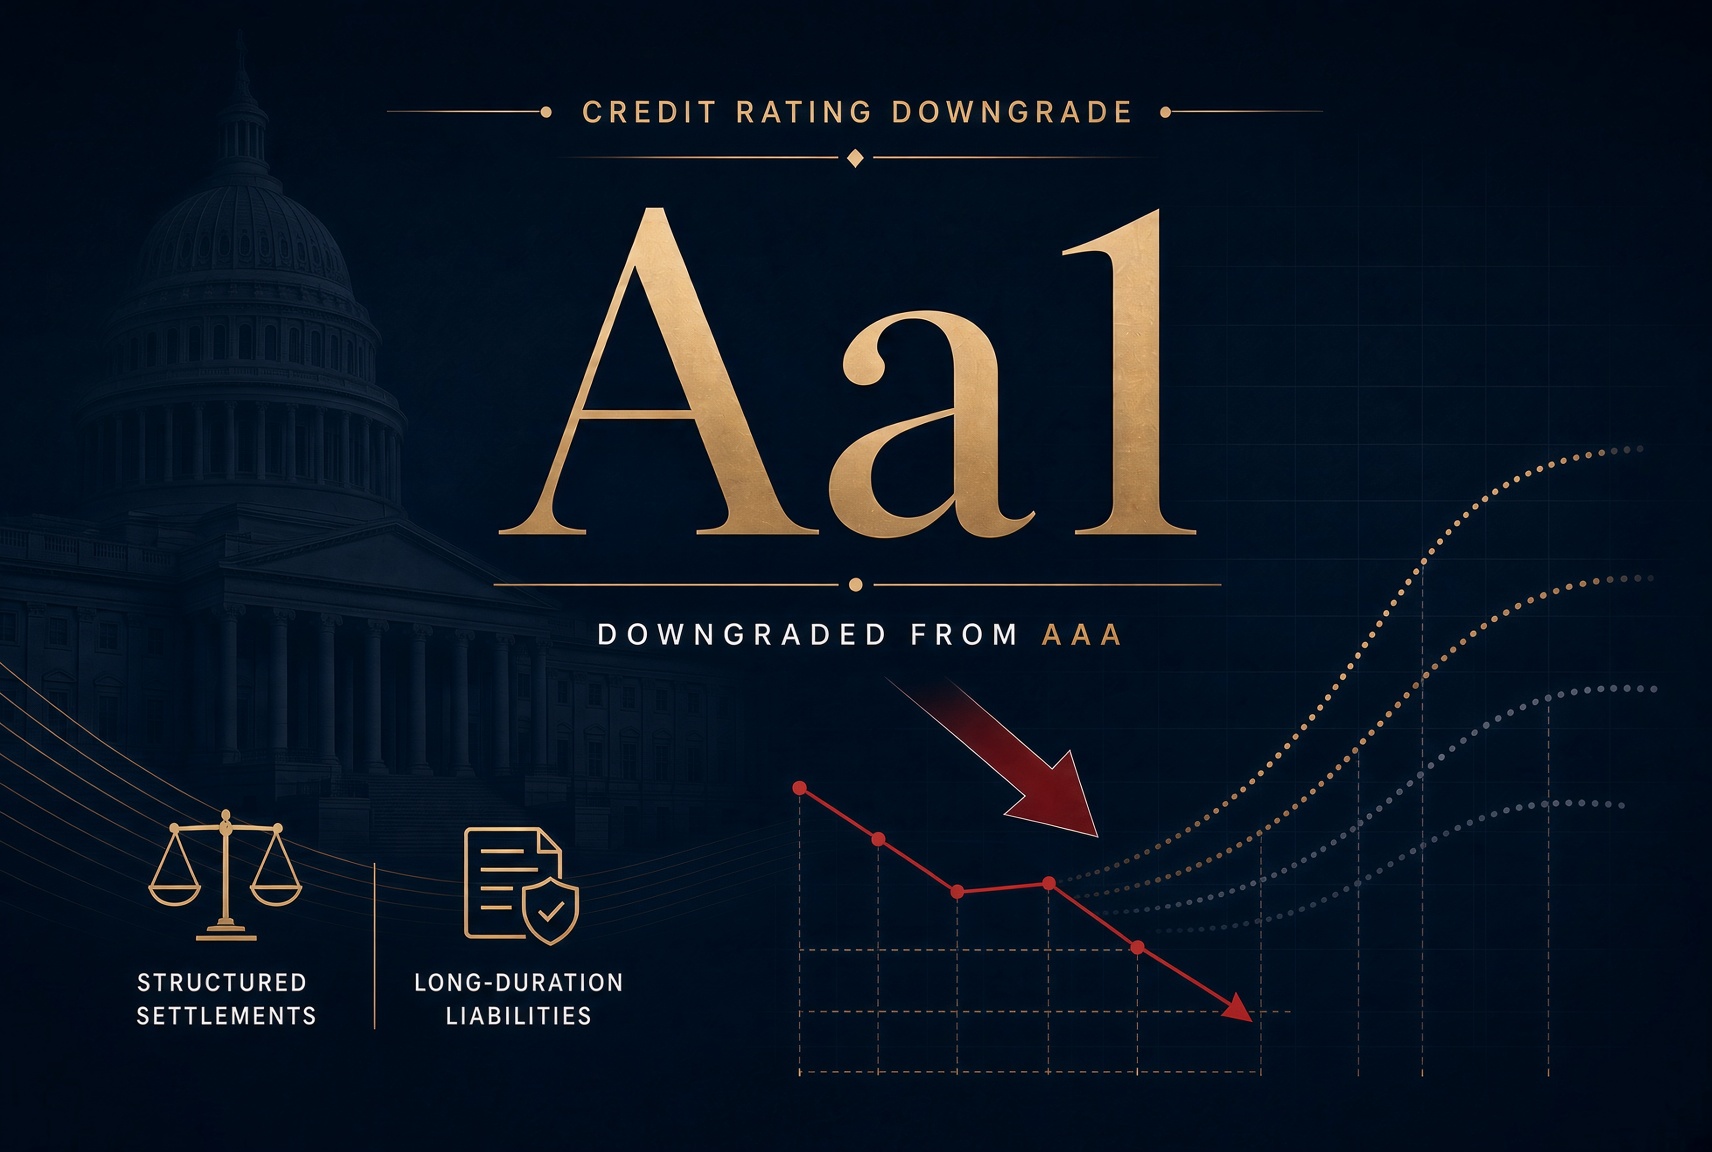
Moody’s Investors Service downgraded the long‑term sovereign credit rating of the United States from Aaa to Aa1, ending more than a century of uninterrupted top‑tier status. This downgrade, completed in May 2025, marked the moment when all three major rating agencies — S&P (2011), Fitch (2023), and now Moody’s — had removed the United States from the AAA category.
What has Happened Since the Downgrade?
The downgrade was not a signal of imminent default risk. It was a structural signal: the cost of capital for long‑duration obligations is rising, and the risk‑free rate is no longer anchored by AAA sovereign credit. Treasury yields have already adjusted upward, with the 10‑year at 4.56% and the 30‑year touching 5.08% during the downgrade window.
For structured settlements, insurers, private‑credit platforms, and long‑tail liability managers — especially those operating in New York, where statutory judgment interest rules create unique pricing dynamics — this shift has direct consequences.
1. What Aa1 Actually Means
Moody’s Aa1 is the second‑highest rating in its scale. It reflects:
very high credit quality,
but rising fiscal pressures,
elevated debt levels (federal debt at $36.2 trillion at downgrade),
and long‑term deficits projected at ~7% of GDP.
Moody’s also projected U.S. debt‑to‑GDP to reach 134% by 2035, reinforcing the rationale for the downgrade.
The downgrade does not imply default risk. It implies higher long‑term borrowing costs — which ripple through every market that prices off the Treasury curve.
2. Treasury Yields and the Cost of Funding Long‑Duration Liabilities
Treasury yields form the base rate for:
structured settlement annuity pricing,
insurer reserve calculations,
private‑credit spreads,
leveraged‑loan coupons,
mezzanine financing,
and long‑tail liability discounting.
When the 30‑year Treasury yield rises — even modestly — every borrowing cost above it rises in parallel. Private‑credit spreads, mezzanine rates, and preferred‑equity hurdles all move upward when the long end of the curve reprices.
This is why the Aa1 downgrade matters: it raises the floor under all long‑duration funding costs.
3. Structured Settlement Pricing: Still More Efficient Than Alternatives
Even with higher Treasury yields, structured settlements remain more efficiently priced than lump‑sum cash or privately financed alternatives.
Why?
Insurers price long‑duration risk more efficiently than banks or private credit.
They rely on:
long‑duration asset‑liability matching,
diversified general‑account portfolios,
stable regulatory capital frameworks,
and institutional access to Treasuries.
Insurers do not rely on short‑term leverage. They do not face rollover risk. They do not depend on wholesale funding markets.
This structural stability keeps structured settlement pricing disciplined and efficient, even in a rising‑rate environment.
4. The New York Structured Judgment Calculation Dynamic: When Present Value Exceeds Nominal Value
New York’s statutory damages growth rate for future awards is 4%, fixed and unwavering.
During April 2020 — when Treasury yields collapsed — the 10‑year Treasury plunged to roughly 0.60%, with longer durations barely above 1%:
10‑year Treasury ≈ 0.60%
20‑year Treasury ≈ 1.00%
30‑year Treasury ≈ 1.20%
This produced a dramatic negative spread. For example:
When future damages grow at 4% but are discounted at ~0.60%, the present value increases, not decreases. And because duration assumptions can vary — including the use of short‑duration or interpolated “bucket interest” inputs — the effective discount rate can be even lower, making the negative spread larger.
Result: A $1 million judgment could have a present valuegreaterthan $1 million.
This is mathematically correct:
the liability accretes,
the present value rises,
the defendant’s economic exposure expands,
and the judgment behaves like a growing asset.
This phenomenon was especially pronounced in New York, where large judgments (including hypothetical Article 50A and 50B exposures) effectively carried a net growth rate because the statutory interest exceeded the discount rate.
5. As Rates Rise, Present Values Normalize
The negative‑spread effect was especially pronounced when discount rates collapsed in 2020 early in the Coronavirus Pandemic. With the statutory 4% growth rate outrunning discounting, present values could exceed nominal values — most visibly in long‑tail components of damages.
CPLR 50‑A adds a simple timing wrinkle: pain and suffering is compressed into eight years with a larger required upfront payment. In large verdicts, especially those subject to appeal, there can be past‑future years before the structured portion begins. That timing shift can amplify the effect when discount rates fall far below the statutory growth rate.
Today, with 10‑year Treasurys around 5.24% (Source: CNBC Treasurys), discount rates sit comfortably above the 4% statutory growth rate. The negative‑spread environment has disappeared, and present values behave normally again.
6. Private Credit: The First Real Stress Test
The downgrade has accelerated stress in private‑credit markets:
refinancing costs are rising,
mezzanine rates are increasing (13.5% → 14.25–14.75% if long‑end yields sustain a 50bps premium),
liquidity is tightening,
and institutional capital is repositioning.
Private credit relies heavily on leverage. Aa1 makes leverage more expensive.
Structured settlements — which do not rely on leverage — retain their pricing advantage.
7. Why This Matters to Readers in Connecticut, New York and Across the United States, including those from elsewherewith claims and litigation in the USA
Readers in:
New York City,
Stamford,
Boston,
Chicago,
Los Angeles,
Miami,
Houston,
nationwide and beyond,
work with long‑duration obligations every day.
The Aa1 downgrade affects:
annuity pricing,
insurer capital costs,
private‑credit spreads,
QSF investment policies,
and the economics of large judgments.
But the core truth remains:
Structured settlements are still priced better because insurers often discount liabilities using Treasuries — the lowest‑cost long‑duration benchmark.
8.Why This Is Good for New York Business
New York — with its:
4% statutory judgment interest
high‑value catastrophic cases
institutional defendants
sophisticated plaintiff bar
complex liability environment
benefits disproportionately from the return of meaningful discounting.
When Treasury yields were near 1% in 2020, New York’s 4% statutory interest created a net growth rate. A $1M judgment could have a present value above $1M. Discounting barely worked.
Now, with Treasuries at 4–5%:
discounting behaves normally
present values fall below nominal values
settlement affordability improves
structured settlements become more attractive
lifetime benefit designs strengthen
insurers regain pricing discipline
plaintiffs receive more stable guarantees
This is good for New York business — and good for national business — because it restores actuarial sanity and capital efficiency.
9. Structured Settlements Are Entering Their Best Pricing Environment Since 2004 — Across Fixed, Indexed, Index‑Linked, and Non‑Qualified Funding‑Agreement Designs
The Moody’s Aa1 downgrade — the first since 1917 — pushed long‑duration Treasury yields to levels not seen in more than two decades. For structured settlements, this is not a headwind. It is a tailwind.
With the 10‑year Treasury in at time of posting at about 5.25% and the 30‑year above 5%, structured settlements now deliver:
≈ 6% tax‑free IRR on many fixed designs
≈ 5% or better over 10‑year horizons
stronger lifetime income guarantees
more affordable defense‑side funding costs
more predictable plaintiff‑side benefit streams
These are rates the industry has not seen since 2004 — and they fundamentally improve the economics of long‑duration liability resolution.
But the modern structured settlement market goes far beyond fixed annuities.
Indexed Structured Settlements
Provide upside potential tied to equity index performance while guaranteeing minimum payments. They offer:
tax‑free growth under §104(a)(2)
annual reset features
downside protection
stronger base guarantees thanks to higher rates
Index‑Linked Structured Settlements
Hybrid designs combining:
guaranteed minimums
index participation
caps or participation rates
annual point‑to‑point crediting
These products did not exist in 2004. They are uniquely suited to today’s rate environment, where higher fixed yields support stronger guaranteed floors.
With today’s yields, these non‑qualified structures are more competitive than at any time in the last 20 years.
Bottom Line
With long‑duration Treasury yields at levels not seen since 2004, structured settlements can now deliver 6% tax‑free returns, 5% or better over 10 years, and modern indexed and index‑linked growth options. Funding‑agreement structures extend these advantages to non‑qualified cases. The Moody’s Aa1 downgrade pushed rates higher, restoring the discounting power that makes structured settlements the most cost‑efficient way to fund long‑duration liabilities in Connecticut, New York, New Jersey and across the United States — and the core truth remains long‑duration benchmarks.
*Editorial Note: Although the London Daily article cited above carries a current October 2026 publication date, the event it describes — Moody’s downgrade of the U.S. credit rating — occurred on May 16, 2025. The resurfacing of the article without historical context may lead readers to interpret the downgrade as newly occurring. The analysis in this post reflects the economic and rate‑environment conditions of 2025, which remain relevant for understanding structured settlement annuity pricing trends and the broader implications of the downgrade.
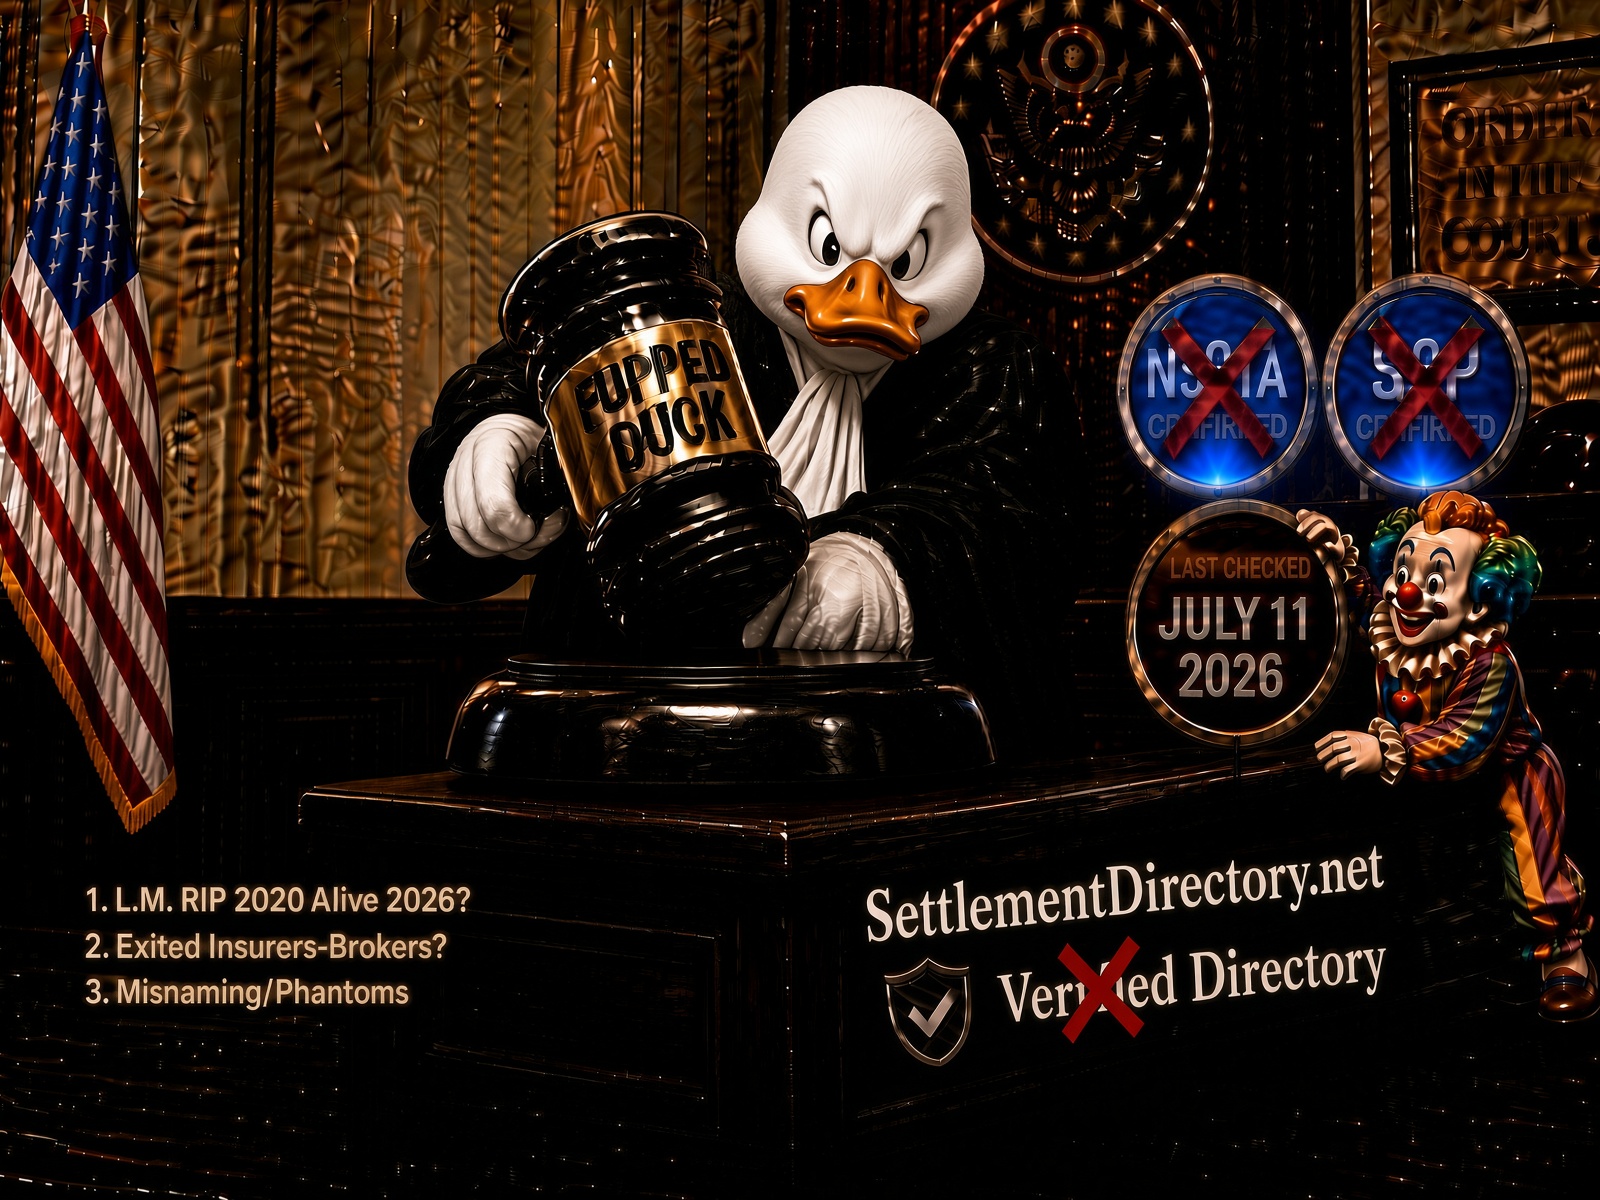
Medium: Scraped data, hallucinated affiliations, fake trust badges, and one very confident July 11, 2026 timestamp applied to everything like ranch dressing at a Golden Corral buffet.
Provenance: SettlementDirectory.net (2024–2026), a site that claims to “verify” structured settlement companies but cannot verify whether its own listings are alive, real, spelled correctly, or exist in this dimension.
🧨 Verification Standards
Based on the actual SettlementDirectory.net Verification Standards page
Before we examine the wreckage of the directory itself, we begin with the Verification Standards — the page where SettlementDirectory.net explains its “rigorous” process.
This is the Rosetta Stone of the fraud.
🔥 1. “Verified” means nothing
They claim:
“Verified label means a listing has passed our current directory review workflow…”
Yet the directory contains:
RIPs listed as active
non‑members listed as NSSTA
exited issuers listed as brokers
misnamed individuals
phantom firms
defunct companies
parked domains
wrong executives with wrong companies
If this is “passing the workflow,” the workflow is a random number generator.
🔥 2. They claim to review business names and category fit
“Review of the published business name, category fit…”
Reality:
“Grant Hickey” — a company that does not exist
“Wrong Company” individuals
insurers listed as brokers
defunct companies listed as buyers
never‑issuers listed as structured settlement companies
RIP from 2020 listed as living July 11, 2026.
Category fit? They don’t have categories — they have category collapse.
🔥 3. They claim to review core fields against public sources
“Review of core directory fields… against the public source material…”
Reality:
RIPs “confirmed”
non‑members “confirmed”
wrong companies “confirmed”
wrong spellings “confirmed”
wrong affiliations “confirmed”
wrong categories “confirmed”
If they reviewed public sources, they reviewed them with their eyes closed.
🔥 4. They claim manual formatting and link review
“Manual formatting and link review…”
Reality:
misspelled names
phantom firms
broken logic
misassigned professionals
dead companies presented as active
dead people claimed by these toads “verified” as alive and active members of multiple trade associations
insurers mislabeled as brokers
Manual review? This is automated scraping with a pulse.❤️🔥🧹
🔥 5. The most damning claim: association badges only shown when confirmed
“Association badges are only shown when we found a matching public membership signal…”
This is the fatal flaw.
Because the directory shows:
MassMutual — NSSTA confirmed (false)
Transamerica — NSSTA confirmed (false)
Symetra — NSSTA confirmed (false)
Guardian — NSSTA confirmed (false)
Northwestern Mutual — NSSTA confirmed (false)
John Hancock — NSSTA confirmed (false)
AIG — NSSTA confirmed (false)
Lars Meyerson — Lars Meyerson won’t be claiming his listing — Lars Meyerson passed away on February 29, 2020, but SettlementDirectory.net still has him marked as “NSSTA & SSP confirmed” July 11, 2026. A simple Google search would have preserved a 1/4 teaspoon of credibilty.
Their own standard says badges appear only when confirmed. The listings prove badges appear even when fabricated.
This is trust‑badge fraud.
🔥 6. They claim a “trust‑audit pass” was completed July 11, 2026
“Last public association membership review pass completed: July 11, 2026.”
This date appears everywhere — even on listings that are:
dead
defunct
misnamed
misassigned
non‑members
exited issuers
phantom firms
parked domains
If July 11, 2026 was a real audit, it was conducted by:
a Roomba
a Magic 8‑Ball
or a random number generator
This timestamp is theater🍿🥸, not verification.
🔥 7. They disclaim licensing and regulatory checks
“We do not claim to perform a 50-state licensing verification…” “We do not claim to run a comprehensive regulatory-action screening…”
Fine. But they do claim:
verified
confirmed
trust‑audited
membership‑checked
public‑directory‑validated
None of which is true.
This is false precision — pretending to be rigorous while disclaiming the only things that would make the directory useful.
🔥 8. They tell users to confirm everything themselves
“Users should still confirm licensing, fees, court-approval requirements…”
Translation:
“We verified nothing. Please do all the work yourself.”
This is the final admission that the directory is totally useless.🎪🤡
🎨 Exhibit Summary
With the Verification Standards exposed as procedural cosplay, we now turn to the directory itself — a monument to content barfing.
SettlementDirectory.net claims to be a “61+ Verified Structured Settlement Companies Directory” with badges like:
NSSTA confirmed
SSP confirmed
SSTA confirmed
Membership confirmed
Last checked July 11, 2026
Yet the directory simultaneously:
lists dead people as active members
lists non‑members as NSSTA
lists exited insurers as brokers
lists never‑issuers as structured settlement companies
lists defunct companies as buyers
lists parked domains as active businesses
lists misnamed individuals with phantom firms
lists executives with the wrong companies
lists my company without permission
and stamps “Last checked July 11, 2026” on every single entry
This is not verification. This is content projectile vomiting.
🧪 Key Artifacts
1. The RIP Badge (Hall of Fame Inductee)
Lars Meyerson (1960–2020) Listed as:
SSTA confirmed
SSP confirmed
“Last checked July 11, 2026”
A dead man “confirmed” in 2026. This is necromancy, not due diligence.
2. The Wrong‑Company Executive
Lists an Athene executive as American General when he has been at Athene for more than a year. But: “Last checked July 11, 2026”
What did they check? Absolutely nothing.
3. The Phantom Firm
Mary Beth Kohl‑Galbraith Real: COO, Brant Hickey Directory: “Grant Hickey” Badge: “Confirmed against public member directories”
A company that doesn’t exist, confirmed against directories that do.
I know Gary Brant and Dave Hickey personally—yeah, for say 33-34 years! My cross-check isn’t powered by Google or a random Wikipedia rabbit hole; it’s fueled by my lived experience, which is like a fine wine that’s just a little bit fermented—definitely not some noisy, half-hearted onomatopoeia!
4. The Misspelled Member
Jorge Aguiar Segura Name wrong. Firm wrong. Badge: SSP confirmed.
This is “scrape → guess → badge” in its purest form.
5. The Insurer‑as‑Broker Hall of Shame
Despite claim of “verifyiing July 11, 2026″…
Featuring:
MassMutual (exited 2007)
Transamerica (exited ~2006)
Symetra (exited-2012)
John Hancock (exited 2013)
Northwestern Mutual (never issued SSAs)
Guardian (never issued SSAs)
AIG (Spun off AIG LIfe & Retirement—>Corebridge)
All listed as: Broker — Structured Settlements — NSSTA confirmed
This is category collapse on a biblical scale.by SettlementDirectory.net.
6. The Defunct Buyer Showcase
Novation
Settlement Capital
Client First
Mainstreet Funding
All listed as active buyers. All dead. All “verified.”
This is digital necromancy with a CSS stylesheet.
🏆 Why This Exhibit Matters
Because SettlementDirectory.net didn’t just barf content — it barfed trust signals, membership badges, verification timestamps, and professional identities.
It is the rare specimen where:
every badge is fake
every category is wrong
every timestamp is meaningless
every “confirmation” is fabricated
every listing is suspect
every insurer is a broker
every defunct company is alive
every misnamed person is “verified”
every RIP is “active”
and every error is confidently stamped with the same date
This is not a directory. This is content projectile vomiting.
🎤 Museum Tagline
“In the grand taxonomy of digital nonsense, SettlementDirectory.net achieves what few dare attempt: it verifies nothing, misclassifies everything, and still has the audacity to timestamp its own hallucinations. Truly, a masterpiece of modern content barfing.” — Upchuck Hurlingham III, Curator, The Corinthian Museum of Content Barfing
Already criticized by the Hon. Judge Duck, Monteverde Equity Partners now finds itself back as the Halloween bench convenes. Judge Duck issues a seasonal warning: Don’t let these goblins gobble up your structured settlement payments.
Key Facts
Monteverde Equity Partners, a structured settlement factoring company already criticized for targeting a 17‑year‑old and for submitting materially flawed “comparable annuity quotes” in a prior New York transfer petition in Saratoga County, now presents a “Carriers & Institutions” page on its website that contains systemic issuer‑identification errors. The company recently filed a petition in Bronx County Supreme Court — Monteverde Equity Partners, LLC v. Pacific Life and Annuity Services, Inc. et al (filed June 8, 2026). UniCourt records confirm the filing: Monteverde Equity Partners, LLC v. Pacific Life and Annuity Services, Inc. et al.
The Carriers & Institutions page lists 34 entities under the heading “Structured Settlement & Annuity Issuers.” For emphasis and clarity, the Carriers & Institutions page’s “Structured Settlement & Annuity Issuers” list is the section under review.
A comparison against three freely accessible public resources — the New York Department of Financial Services (DFS) Insurance Company Search, New York Insurance Law §1113(a), and the Life Insurance Council of New York (LICONY) member directory — shows that a substantial majority of those 34 entries contain at least one material inaccuracy.
These resources require no subscription, no login, and no specialized knowledge to use.
The Three Free Public Resources
1. The NY DFS Insurance Company Search The DFS portal allows any user to search every insurer licensed to do business in New York by name, NAIC number, group code, or line of business. It returns exact legal names and the specific “Writing Powers” — the lines of business (keyed to §1113(a) paragraph numbers) each carrier is authorized to write. DFS PortalDFS Portal. Insurance Company Search – Guest Applications – DFS Portal It is updated continuously.
2. New York Insurance Law §1113(a)This is the foundational statutory framework for licensed insurance in New York. Paragraph (1) defines “Life Insurance.” Paragraph (2) defines “Annuities” as “all agreements to make periodical payments for a period certain or where the making or continuance of all or some of a series of such payments, or the amount of any such payment, depends upon the continuance of human life.” NewYork.Public.LawNewYork.Public.Law. N.Y. Insurance Law Section 1113 – Kinds of insurance authorized (2026) Critically, the DFS writing-powers table appended to the statute contains explicit statutory bars: for paragraphs 1 (Life) and 2 (Annuities), the table states: “Property and Casualty companies are not permitted to write this kind of insurance.” Department of Financial ServicesDepartment of Financial Services. Insurance Companies: Insurance Company Search | Department of Financial Services This is not an obscure regulatory opinion — it is printed directly on the DFS website.
3. The LICONY Domestic Member List The Life Insurance Council of New York publishes a free public directory of its 53 domestic and 21 foreign member companies — the companies that collectively provide the vast majority of annuities and life insurance to New Yorkers. Life Insurance Council of New YorkLife Insurance Council of New York. Members – Life Insurance Council of New York The list is sorted alphabetically, includes exact legal names, and links to each company’s website. It is the fastest single-stop verification tool for confirming whether a named entity is actually a NY-licensed life/annuity issuer.
This is the most fundamental class of error. §1113(a) and the DFS writing-powers table are unambiguous: P&C carriers cannot issue annuities in New York. Yet Monteverde’s page lists nine P&C carriers as entities for which they “successfully process” structured settlement transfers:
Entity Listed
Actual Classification
What the DFS Search Shows
American Home Assurance Company
AIG P&C subsidiary
Writing powers: fire, liability, marine — no life or annuity
Amica Mutual Insurance Company
P&C mutual carrier
Separate entity from Amica Life Insurance Company (LICONY associate member)
Arrowood Indemnity Company
P&C run-off carrier (fmr. Royal & SunAlliance)
P&C lines only
Fireman’s Fund Insurance Company
P&C; in wind-down since 2014
Cannot write new business of any kind
Hartford Insurance Company of the Midwest
P&C commercial lines
No life or annuity authority
Hartford Underwriters Insurance Company
P&C commercial lines
No life or annuity authority
Nutmeg Insurance Company
Hartford P&C subsidiary
P&C lines only
State Farm Fire & Casualty Co
P&C
Correct entity for annuities is State Farm Life & Accident Assurance Company (LICONY associate member)
Travelers Casualty & Surety Company
P&C surety carrier
No annuity authority
In each case where there is a correct affiliated life/annuity entity (Amica Life, State Farm Life & Accident), Monteverde lists the wrong company in the same family — the brand name that people recognize, not the licensed insurer.
The Hartford situation is particularly illustrative: three separate Hartford entities appear on the page (CEBSCO, Insurance Company of the Midwest, and Hartford Underwriters), and none of them is the Hartford entity that actually issued structured settlement annuities — which would be Hartford Life Insurance Company or Hartford Life and Accident Insurance Company. Neither of those appears on the list at all.
Error Category 2: Assignment Companies and SPEs Listed as Issuers (15 Entities)
More than half the entries on Monteverde’s page — 15 of 34 — are not annuity issuers. They are qualified assignment companies (QACs) or special purpose entities (SPEs): the intermediary shells used in IRC §130 qualified assignments to hold periodic payment obligations. The QAC assumes the obligation from the settling defendant or liability carrier; the backing life insurance company writes the annuity that funds those payments. Listing a QAC as an “annuity issuer” confuses the assignment obligor with the underwriting insurer — a foundational distinction in structured settlement law.
QAC/SPE Listed
Actual Annuity Issuer (LICONY Member)
American General Annuity Service Corporation
United States Life Insurance Company in the City of New York American General Life Insurance Company
Athene London Assignment Corporation
Athene Annuity & Life Assurance Company of New York ✓
Equitable Structured Settlement Corp
Equitable Financial Life Insurance Company ✓
Farmers Services Corporation
Farmers New World Life Insurance Company
GE Capital Assignment Corporation
Legacy block (now in various run-off/assumption arrangements)
Genworth Annuity Service Corporation
Genworth Life Insurance Company of New York ✓
Hartford CEBSCO
Hartford Life Insurance Company
Independent Assignment Company
Independent Life Insurnace Company (NOT Licensed in New York)
John Hancock Assignment Company
John Hancock Life Insurance Company of New York ✓
Lincoln Assignment Corporation
Lincoln Life & Annuity Company of New York ✓
Massmutual Assignment Company
Massachusetts Mutual Life Insurance Company ✓
Mutual of Omaha Structured Settlement Company
United of Omaha Life Insurance Company
Prudential Assignment Settlement Service
The Prudential Insurance Company of America ✓
Symetra Assigned Benefits Service Company
First Symetra National Life Insurance Company of New York ✓
WILCAC Structured Settlements Inc.
Wilton Re / Everlake Life Insurance Company
(✓ = LICONY member or associate member) Life Insurance Council of New YorkLife Insurance Council of New York. Member Companies – Life Insurance Council of New York
A simple DFS search for any of these QAC names would return either no results or a result showing no writing powers — because QACs are not licensed insurers. The LICONY list would immediately surface the correct parent issuer.
Error Category 3: Incorrect or Imprecise Legal Names (8 Entities)
Even among the legitimate life/annuity issuers on the list, several are named incorrectly in ways that would be consequential if these names appeared in court petitions or disclosure statements:
“Berkshire Hathaway (BHG Structured Settlement)” — Berkshire Hathaway Inc. is a holding company, not a licensed insurer. The relevant entities are Berkshire Hathaway Life Insurance Company of Nebraska or General Re Life Corporation. “BHG Structured Settlement” is not a licensed insurer name.
“Metropolitan Life (MetLife Tower Resources)” — The licensed insurer is Metropolitan Life Insurance Company. “MetLife Tower Resources” was an internal program name, not a legal entity, and does not appear in the DFS licensing database. MetLife Tower Resource Group, Inc. is the qualified assignment company where structured settlement annuities are issued by Metropolitan Life Insurance Company.
“New York Life Insurance” — Missing the word “Company.” The licensed entity is New York Life Insurance Company. For annuity-specific transactions, the relevant subsidiary New York Life Insurance and Annuity Corporation.is the qualified assignment company.
“Pacific Life & Annuity” — The NY-authorized subsidiary is Pacific Life and Annuity Company. The irony: Monteverde Equity Partners has a pending Supreme Court case against Pacific Life and Annuity Services, Inc. — a servicing entity — and yet uses an abbreviated form of Pacific Life’s name on their own website. Source: UniCourt. Monteverde Equity Partners, LLC v Pacific Life and Annuity Services, Inc et al
“United States Life Insurance Company” — The correct full legal name, as listed by LICONY, is United States Life Insurance Company in the City of New York (part of Corebridge Financial). Dropping the jurisdictional suffix creates ambiguity with parent entities organized in other states. Life Insurance Council of New YorkLife Insurance Council of New York. Member Companies – Life Insurance Council of New York
“Talcott Resolution Life and Annuity Insurance” — Missing the word “Company” at the end. The correct name is Talcott Resolution Life and Annuity Insurance Company (formerly Hartford Life and Annuity Insurance Company).
“Wilton/Everlake (Formerly Allstate)” — This conflates two distinct regulatory histories. Wilton Re assumed the former Allstate Life Insurance Company of New York block; the resulting entity rebranded as Everlake Life Insurance Company. These are sequential legal successor entities with separate DFS filings — not a unified “Wilton/Everlake.”
“Jamestown Life Insurance Company” — No entity by this name appears to be currently or historically licensed as a New York insurer in the DFS database or on the LICONY member list. It is unclear what entity this is intended to reference.
Error Category 4: Stale or Defunct Entities Presented as Active (2 Entities)
Guaranty Association Benefits Company (GABC) was a special-purpose entity created to assume the obligations of the failed Executive Life Insurance Company of New York (ELNY) following its 1991 insolvency. As of July 1, 2026, Pacific Life assumed GABC’s remaining annuity obligations. Listing GABC as a current operational carrier at the time this analysis is written (October 2026) means the entry is factually outdated by over three months. catalinastructuredfunding.comcatalinastructuredfunding.com. Structured Settlement Annuity Companies: Full Issuer List | Catalina
Fireman’s Fund Insurance Company — beyond the §1113(a) disqualification noted above, Allianz wound down Fireman’s Fund’s U.S. operations beginning in 2014. It is not writing new business and has not been for over a decade.
Why This Matters Beyond the Website
The Carriers & Institutions page describes itself as a showcase of entities for which Monteverde “successfully processes” transfers. If the entity names displayed publicly are inaccurate, the same inaccuracies plausibly carry forward into:
Disclosure statements filed with transferors under the New York Structured Settlement Protection Act (SSPA), which require identification of the annuity issuer
Court petitions seeking judicial approval of transfers, where the court and opposing parties rely on accurate issuer identification to evaluate the transaction
Contact and verification with the actual annuity servicer or obligor — a process that breaks down when the entity name used doesn’t match the licensed insurer’s name in the insurer’s own records
The pending matter in Bronx County — where Monteverde sued Pacific Life and Annuity Services, Inc. (a servicing company) alongside Pacific Life and Company (the parent holding company) — raises its own questions about whether the correct licensed NY subsidiary was properly identified in those filings. UniCourtUniCourt. Monteverde Equity Partners, LLC v Pacific Life and Annuity Services, Inc et al
What a Proper Methodology Looks Like
A factoring company operating in this space should, at minimum, do the following before listing any entity as an issuer:
DFS Name Search → confirm the exact legal name and domicile state of the licensed insurer
DFS Writing Powers → confirm the insurer holds paragraph 2 (Annuities) authority in New York; confirm it is not exclusively a P&C carrier
LICONY Cross-Check → confirm membership/association status for NY-market issuers; note the correct domestic NY subsidiary vs. out-of-state parent
QAC vs. Issuer Distinction → if a named entity ends in “Assignment Corporation,” “Settlement Service,” “Assignment Company,” or similar, search for the backing life insurer, not the QAC itself
Currency Check → confirm the entity is still licensed and writing business (or at minimum, that its legacy obligations have not been transferred to a successor)
Three public websites. No cost. No specialized access. The DFS database alone would have eliminated virtually every error in every category above.
Pacific Structured Assets (Catalina) –——>”the underlying structured settlement was originally funded by an insurance company purchasing an annuity for the claimant. When the claimant sells their payments, the investor steps into the payment stream — but not into the annuity contract. The industry adopted the term “secondary market annuity,” but it is a misnomer” Greg Saber, Esq. reviewed July 27, 2026
Important Technical Point: Very few structured settlement annuities are purchased by an insurance company. Structured settlement annuities are purchased by qualified assignment compaies in most cases, non qualified assignment companies in many cases and in some instances by self insured Defendants. A few examples would be where the structured settlement is being funded by a self-insured defendant, or a Defendant within its retention, The United States of America, to resolve claims under the Federal Tort Claims Act.
Todd Lesk
And then we have Todd Lesk and MJ Settlements
I’ll let the words of Greg Saber, who is a licensed attorney and a principal in Catalina Funding, underscore the point.
“Important distinction: Buying a secondary market annuity does not create a new annuity contract in your name. You step in as the new recipient of a stream of payments that already exists. No insurer issues you a policy, which is exactly why the protections below work differently for you than they would for the original owner” Saber Ibid..
📌Summing it Up
Structured settlement receivables are not annuities
No new annuity contract established when transacting receivables
Annuitant doesn’t own the annuity contract in a legitimate structured settlement
The “original owner” and “owner of the annuity after any transfer of structured settlement payment rights” remains the qualified assignment company
No state insurance law, regulation, bulletin, administrative rule, or statutory definition anywhere in the United States uses the term “secondary market annuities.” Search across state insurance codes, annuity statutes, SSPA statutes, and regulatory materials shows zero occurrences of the term in any official government source.
The term is exclusively a private‑sector marketing invention, not a legal or regulatory category.
Genex Capital recently added a clear, direct disclosure in its online presence that tells consumers exactly who funds and completes their structured settlement transactions. It’s a simple, effective improvement that makes the process easier to understand for sellers navigating an unfamiliar space. In a market where transparency can vary, this kind of straightforward clarity is good work — and worth acknowledging.
Sell My Structured Settlement for Cash (SMSSC) has also introduced a disclosure about how its industry‑related content is reviewed. Accuracy is now attributed to Kevin Lowe, MBA, Chief Operating Officer of Genex Capital, noting his more than eleven years inside the structured settlement industry (secondary market) and his experience overseeing legal processing teams that take transfers through court. Pages he has reviewed carry his byline and a review date, and the site publishes its sourcing and corrections process in its editorial standards. The appearance of a senior executive’s byline on consumer‑facing material is a recent development, and it reflects a willingness to stand behind the information being presented.
Regardless of who operates a site, consumers deserve to know who’s behind it before sharing sensitive details.
Taken together, these updates reflect a thoughtful approach to how information is presented and how consumers are guided through a process that can feel unfamiliar.
Clear disclosures speak for themselves, and this one speaks well.